
Disability and Long-Term Care Insurance Cost-Benefit Analysis for Small Business Owners
For small business owners, the greatest threat to financial stability is often not market volatility, but personal health crises. Data indicates that one in four workers will experience a disability before reaching retirement age. When a business owner cannot work, the revenue stream vanishes, yet fixed expenses remain. This guide analyzes the cost-benefit ratio of disability and long-term care insurance, demonstrating how these tools protect business equity and personal wealth.
Why Business Owners Need Disability Insurance
Small business owners are the engine of their companies. Unlike salaried employees who may have short-term disability coverage, business owners often lack any income protection if they become unable to work. Disability insurance is designed to replace a portion of your income if you are unable to earn a living due to illness or injury.
The cost of disability insurance varies based on age, occupation, and health status. However, the benefit is immediate cash flow replacement. Without this coverage, business owners often deplete personal savings, sell business assets at a loss, or incur high-interest debt to keep operations running. This is where the cost-benefit analysis becomes critical. The premium paid is a fraction of the potential financial ruin avoided.
At Generational Wealth Concepts, we specialize in disability income protection tailored for self-employed professionals. Our approach ensures that your business continues to thrive even when you are not physically present to manage it.
Understanding Long-Term Care Costs
Long-term care (LTC) insurance covers services that help you with daily living activities, such as bathing, dressing, and eating, if you become chronically ill or disabled. The costs associated with long-term care are rising rapidly. According to recent industry reports, the average annual cost of a private room in a nursing home exceeds $100,000 in many parts of the United States.
For small business owners, paying for long-term care out-of-pocket can devastate business capital. Many owners mistakenly believe that their business assets are separate from their personal liabilities. However, lenders often require personal guarantees, meaning business assets can be seized to cover personal debts, including medical bills.
Long-term care insurance provides a dedicated pool of funds for these expenses, preserving your business equity. It allows you to choose where you receive care, whether at home or in a facility, without draining your business accounts. This separation of personal health risks from business financial health is a cornerstone of sustainable entrepreneurship.
Cost-Benefit Analysis: Premiums vs. Protection
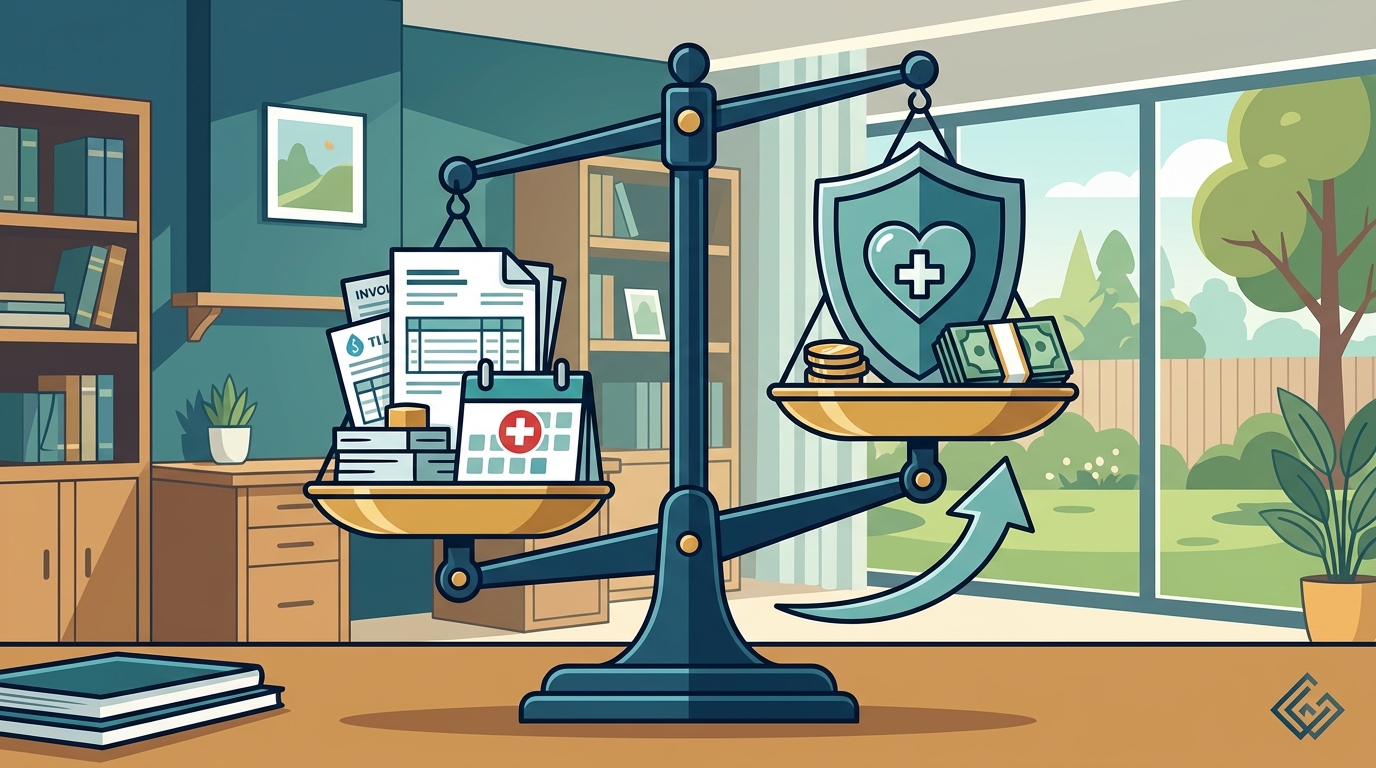
Evaluating the cost-benefit ratio of insurance requires looking beyond the monthly premium. You must consider the probability of claim and the severity of the financial impact. For a small business owner, the "benefit" is not just income replacement; it is business continuity.
Consider the following scenario: A business owner incurs a disability that lasts for two years. Without insurance, they might lose $200,000 in personal savings and $150,000 in business revenue. The total financial hit is $350,000. The annual premium for a comprehensive disability and long-term care policy might be $5,000. Over two years, the cost is $10,000. The benefit-to-cost ratio is 35:1. This is a highly favorable return on investment when measured against risk mitigation.
Furthermore, insurance premiums are often tax-deductible for business owners, further reducing the net cost. When you factor in tax advantages and the preservation of business goodwill, the cost of insurance becomes negligible compared to the potential loss.
Integration with Privatized Banking
One of the most powerful strategies for small business owners is integrating disability and long-term care insurance with Privatized Banking concepts. Privatized Banking uses dividend-paying whole life insurance policies to create a private bank that you control. This "bank" can be used to finance business investments, pay off debt, or cover emergency expenses.
When you have robust disability and long-term care coverage, your personal financial foundation is secure. This security allows you to leverage your Privatized Banking strategy more aggressively. For example, if you face a health crisis, your disability insurance replaces your income, while your Privatized Banking "bank" can provide liquidity for business needs without disrupting your personal cash flow.
This dual-layered approach ensures that neither your health nor your business is compromised by unforeseen events. It allows you to "be the bank" for your business, maintaining control over your financial destiny. For more information on how Privatized Banking works, visit our Privatized Banking page.
Comparison of Insurance Options
Choosing the right insurance products requires understanding the differences between various options. Below is a comparison of key insurance types relevant to small business owners.
| Insurance Type | Primary Benefit | Best For | Cost Factor |
|---|---|---|---|
| Disability Income Insurance | Replaces lost income during disability | Self-employed professionals | Medium to High |
| Long-Term Care Insurance | Covers daily living costs in chronic illness | Business owners with significant assets | High |
| Whole Life Insurance | Cash value growth and death benefit | Wealth building and estate planning | High |
| Fixed Indexed Annuities | Guaranteed income in retirement | Retirement income planning | Medium |
Each of these products serves a distinct purpose. Disability insurance protects your earning power. Long-term care insurance protects your assets from healthcare costs. Whole life insurance builds cash value for future use. Annuities provide guaranteed retirement income. A comprehensive strategy integrates all these elements to create a resilient financial plan.
Key Takeaways
- One in four workers will experience a disability before retirement, making disability insurance essential for business continuity.
- Long-term care costs can exceed $100,000 annually, threatening business equity if not insured.
- The cost-benefit ratio of insurance is highly favorable when measuring premiums against potential business loss.
- Privatized Banking allows business owners to leverage cash value for business needs while maintaining personal protection.
- Disability and long-term care insurance premiums may be tax-deductible, reducing the net cost of coverage.
- Integrating insurance with a Privatized Banking strategy creates a multi-layered financial safety net.
- Small business owners should consult with a wealth coach to design a customized insurance plan.
Frequently Asked Questions
How much disability insurance does a small business owner need?
Most financial experts recommend that small business owners carry disability insurance that replaces 60-80% of their gross income. This ensures that personal and business expenses can be covered while you recover.
Is long-term care insurance tax-deductible?
In many cases, long-term care insurance premiums are tax-deductible as a medical expense, subject to certain limits based on age and income. Consult a tax professional for specific advice.
Can I use my life insurance policy to cover business debts?
Yes, if you are the beneficiary or if the policy is owned by the business, the death benefit can be used to pay off business debts or buy out a partner's share. This is a key component of mortgage protection and business succession planning.
What is the difference between short-term and long-term disability insurance?
Short-term disability covers a brief period, typically 3-6 months, while long-term disability can provide benefits for years or until retirement age. Small business owners often need both to cover the gap between injury and recovery.
How does Privatized Banking help with insurance premiums?
Privatized Banking uses the cash value of a whole life policy as collateral to finance expenses, including insurance premiums. This allows you to keep your cash working for you while still paying for necessary coverage.
When should I start buying long-term care insurance?
It is generally recommended to purchase long-term care insurance in your 50s or early 60s. Waiting too long can result in higher premiums or denial of coverage due to health issues.
Do I need disability insurance if I have savings?
Yes. Savings can be depleted quickly by medical bills and lost income. Disability insurance provides a steady stream of income that preserves your savings for future growth or retirement.
Next Steps
Protecting your business and your wealth requires proactive planning. Do not wait for a crisis to evaluate your insurance needs. At Generational Wealth Concepts, we help small business owners design comprehensive financial strategies that integrate disability, long-term care, and Privatized Banking solutions.
Schedule a free strategy session today to discuss your specific needs and learn how you can build a financially independent future. Contact us at Generational Wealth Concepts to get started.