
Retirement planning in 2026 requires a nuanced approach to income stability. According to recent industry analyses, the integration of permanent life insurance and annuities can significantly improve modeled retirement-income outcomes compared to investment-only strategies. This shift highlights the growing importance of understanding the distinct roles these two financial vehicles play in a comprehensive wealth strategy. Many individuals mistakenly view them as interchangeable, yet their structural mechanics serve fundamentally different purposes in building generational wealth.
Understanding the Basics
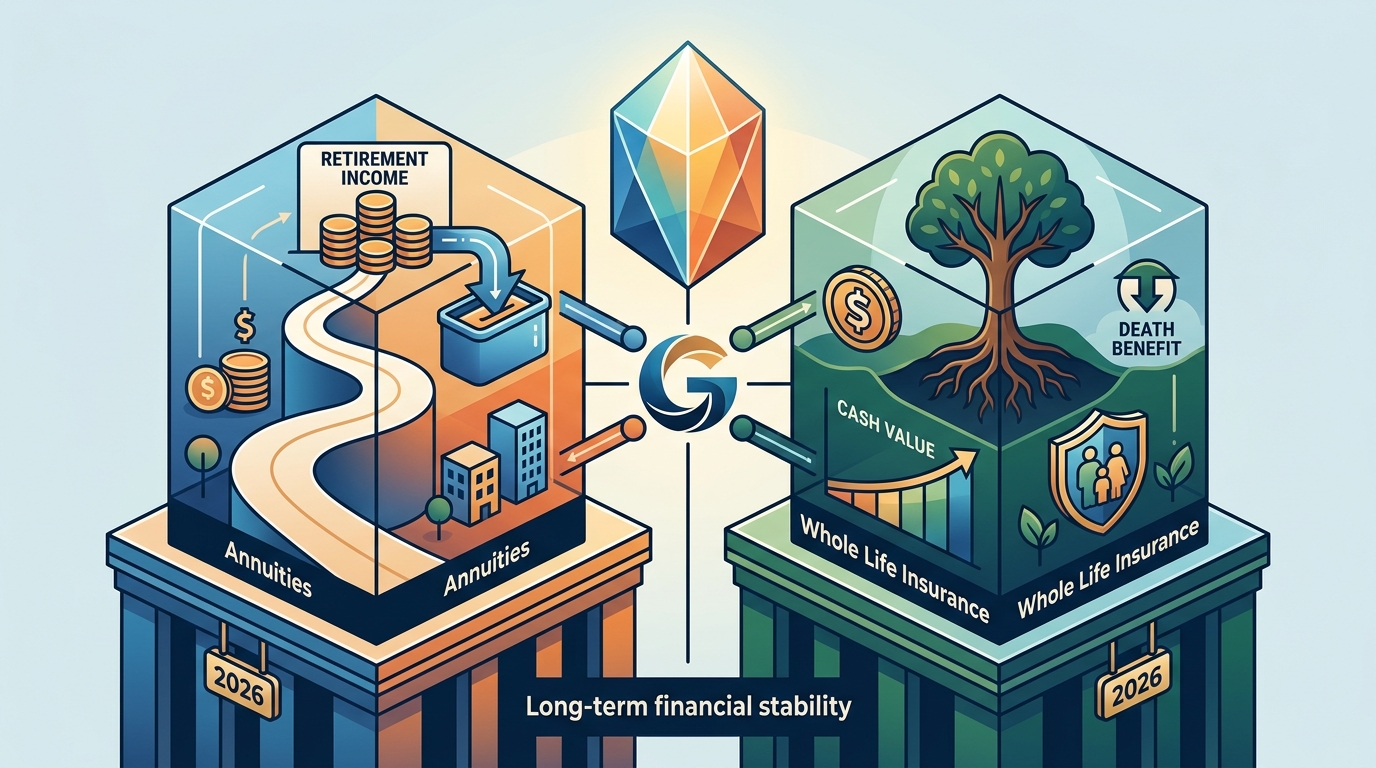
To make an informed decision, one must first define the core nature of each instrument. Fixed Indexed Annuities (FIAs) are insurance contracts that offer interest-crediting potential linked to a market index while protecting principal from direct market losses. They are primarily designed to mitigate longevity risk and provide a predictable income floor.
Conversely, Whole Life Insurance is a form of permanent life insurance that provides a guaranteed death benefit alongside a savings component known as cash value. Unlike variable products, the cash value in a participating whole life policy grows at a guaranteed rate, often supplemented by non-guaranteed dividends. This structure allows for both protection and accumulation, serving as a foundational pillar for privatized banking strategies.
At Generational Wealth Concepts, we emphasize that these tools are not mutually exclusive. Instead, they function as complementary components of a broader financial ecosystem. Understanding their individual mechanics is the first step toward coordinating a strategy that aligns with your specific timeline and risk tolerance.
Income Generation Mechanics
The primary driver for choosing between these two options often hinges on how you intend to generate income during retirement. Annuities are engineered specifically for this purpose. They can convert a lump sum of savings into a guaranteed monthly paycheck that lasts for life. This feature is particularly valuable for individuals who fear outliving their assets.
Whole life insurance, while not an income product by default, offers a different pathway to liquidity. Through policy loans, policyholders can access their accumulated cash value tax-free. This mechanism is the cornerstone of the Infinite Banking Concept, allowing individuals to use their insurance policy as a personal bank. Instead of withdrawing funds and triggering taxes or penalties, you borrow against your asset, keeping the full cash value intact to continue growing.
For those seeking immediate, guaranteed income without the complexity of managing loans, annuities provide a straightforward solution. For those prioritizing control and liquidity, whole life insurance offers a flexible reservoir of capital that can be deployed for investments, business opportunities, or emergency needs.
Cash Value Growth and Liquidity
Growth potential is a critical differentiator. Fixed indexed annuities offer interest rates tied to market indices, such as the S&P 500, but with a cap on gains and a floor on losses. This means you participate in market upside without the risk of direct downside. However, the growth is strictly contractual and limited to the terms set by the insurer.
Whole life insurance offers a dual-growth engine. The cash value grows at a guaranteed minimum rate, providing stability. Additionally, participating policies may pay dividends, which can be used to purchase additional paid-up insurance, further increasing the death benefit and cash value. This compounding effect can be powerful over decades.
Liquidity differs significantly between the two. Annuities often impose surrender charges if funds are withdrawn early, typically lasting several years. This illiquidity is a feature, not a bug, as it prevents premature depletion of retirement income. Whole life insurance, however, is designed for accessibility. Policy loans allow for immediate access to cash value without surrender charges, making it a more liquid asset for dynamic financial planning.
Tax Implications and Efficiency
Tax efficiency is a major consideration for high-net-worth individuals. Both annuities and whole life insurance offer tax-deferred growth, meaning you do not pay taxes on the earnings until you withdraw them. However, the withdrawal mechanics differ.
With annuities, withdrawals are taxed as ordinary income. If you withdraw gains before age 59½, you may also face a 10% penalty. This makes annuities less suitable for short-term liquidity needs. Whole life insurance, on the other hand, allows for tax-free access to cash value through policy loans. As long as the policy remains in force, these loans do not trigger taxable events. This tax advantage is a key reason why many entrepreneurs and professionals prefer whole life for wealth accumulation.
Furthermore, the death benefit from both products is generally income-tax-free to beneficiaries. However, whole life insurance offers more flexibility in how the death benefit is structured and distributed, allowing for complex estate planning strategies that can minimize estate taxes.
Legacy Planning and Protection
Legacy planning is a core mission for Generational Wealth Concepts. Both annuities and whole life insurance can serve as legacy tools, but they do so in different ways. Annuities can include optional death benefits, ensuring that any remaining value passes to heirs. However, these benefits often come at the cost of reduced income payments.
Whole life insurance is inherently a legacy product. The death benefit is guaranteed, provided premiums are paid. It can be used to equalize inheritances, fund charitable gifts, or provide liquidity to pay estate taxes. Additionally, the cash value can be accessed during your lifetime to support your legacy goals, such as funding a grandchild's education or starting a family business.
For families seeking to protect their assets from long-term care costs, hybrid annuities with long-term care riders offer a unique solution. These products allow unused death benefits to be converted into long-term care benefits, providing a safety net that whole life insurance does not inherently offer without additional riders.
Strategic Comparison
The following table summarizes the key differences between fixed indexed annuities and whole life insurance to help you evaluate which aligns with your financial goals.
| Feature | Fixed Indexed Annuity (FIA) | Whole Life Insurance |
|---|---|---|
| Primary Goal | Guaranteed lifetime income | Wealth accumulation and legacy |
| Growth Potential | Linked to market index, capped gains | Guaranteed + potential dividends |
| Liquidity | Low (surrender charges apply) | High (policy loans available) |
| Tax Treatment | Tax-deferred, taxed as income on withdrawal | Tax-deferred, tax-free via policy loans |
| Death Benefit | Optional, may reduce income | Guaranteed, core feature |
| Best For | Longevity risk mitigation | Privatized banking and estate planning |
Key Takeaways
- Income vs. Liquidity: Annuities excel at providing guaranteed income, while whole life insurance offers superior liquidity through policy loans.
- Tax Efficiency: Whole life insurance allows for tax-free access to cash value, whereas annuity withdrawals are taxed as ordinary income.
- Growth Mechanisms: FIAs protect against market downturns, while whole life offers guaranteed growth plus potential dividends.
- Legacy Focus: Whole life is inherently designed for legacy planning, while annuities focus on the individual's lifetime income.
- Coordination is Key: Integrating both products can create a robust strategy that balances income, protection, and liquidity.
- Professional Guidance: Complex tax and estate implications require coordination with specialized professionals for optimal results.
- Personalization: The "best" choice depends entirely on your unique timeline, risk tolerance, and legacy goals.
Frequently Asked Questions
Can I use whole life insurance for retirement income?
Yes, you can access the cash value of a whole life policy through loans or withdrawals to supplement retirement income. This method offers tax advantages and liquidity that annuities may not provide.
Are fixed indexed annuities safe from market losses?
Yes, fixed indexed annuities protect your principal from direct market losses. Your interest credits are based on the performance of a market index, but you do not lose money if the index declines.
What is the Infinite Banking Concept?
The Infinite Banking Concept is a strategy that uses the cash value of a participating whole life insurance policy as a personal banking system. It allows you to borrow against your policy for investments or expenses while keeping the full cash value growing.
Which is better for long-term care planning?
Hybrid annuities with long-term care riders are specifically designed for this purpose. However, whole life insurance can also be part of a broader strategy to fund long-term care costs through policy loans or by selling the policy.
Do I need both annuities and whole life insurance?
Not necessarily. The right choice depends on your individual needs. Many clients benefit from a coordinated approach that uses annuities for guaranteed income and whole life for liquidity and legacy.
How do taxes affect annuity withdrawals?
Annuity withdrawals are taxed as ordinary income. If you withdraw gains before age 59½, you may also face a 10% early withdrawal penalty. It is important to plan withdrawals carefully to minimize tax impact.
Can whole life insurance policies pay dividends?
Yes, participating whole life insurance policies may pay dividends. These dividends are not guaranteed but have a long history of consistency. They can be used to increase the death benefit or cash value.
Next Steps
Choosing between annuities and whole life insurance is not about picking a winner, but about selecting the right tool for your financial blueprint. At Generational Wealth Concepts, we help individuals, families, and business owners coordinate these strategies to build a financially independent lifestyle. Whether you are looking to protect your income, create lifetime retirement paychecks, or build wealth with guarantees, we can design a plan that sets up your future with confidence.
Do not navigate this complex landscape alone. Schedule a FREE Strategy Session today to explore how these tools can work together to secure your retirement and legacy. Contact us at (877) 323-8432 ext 800 or visit our Contact page to get started.