
Financial independence is not built by accident. It is engineered through a combination of risk management and strategic capital allocation. For many professionals and business owners, the choice between protecting their current earning power and building a private banking system often feels like a binary decision. However, the most effective financial architectures utilize both. According to recent industry data, the average American spends approximately 34.5% of their income on debt interest, while the national savings rate hovers around 6%. This disparity highlights the urgent need for strategies that not only protect income but also recapture lost capital.
Understanding Disability Income Protection
Disability income protection is the foundational layer of any robust financial plan. It is designed to replace a portion of your earned income if you are unable to work due to illness or injury. For self-employed professionals and business owners, this is not just an insurance product; it is a business continuity tool.
At Generational Wealth Concepts, we specialize in Disability Income Protection for Self-Employed & Professionals. Unlike standard group policies, individual disability insurance can be tailored to your specific occupation, benefit period, and elimination period. The primary goal is to ensure that a catastrophic health event does not derail your long-term wealth accumulation.
Without this protection, a single accident could force you to liquidate investments at a loss or incur high-interest debt. This is where the concept of income replacement becomes critical. It preserves your ability to contribute to other wealth-building vehicles, including the strategies discussed below.
The Mechanics of Privatized Banking
Privatized banking, often referred to as the Infinite Banking Concept, is a strategy that utilizes a dividend-paying whole life insurance policy to create a personal banking system. This is not a traditional bank account. Instead, it is a private financial infrastructure that you control.
Here is how it works: You fund a whole life policy with the goal of maximizing its cash value. As the policy grows, you can take loans against this cash value to finance major purchases, such as real estate or business equipment. Crucially, while you are using the borrowed capital, your entire cash value continues to grow tax-deferred. You are essentially paying interest to yourself rather than a traditional financial institution.
For more details on this approach, explore our Privatized Banking services. This strategy allows you to recapture the interest you would otherwise pay to banks, effectively increasing your overall savings rate by over 400% in some scenarios.
Comparing Risk Management Features
While both strategies involve insurance, their risk management profiles are fundamentally different. Disability income protection manages the risk of income loss. Privatized banking manages the risk of capital inefficiency.
| Feature | Disability Income Protection | Privatized Banking |
|---|---|---|
| Primary Risk Mitigated | Loss of earning capacity due to injury/illness | Loss of interest income and capital liquidity |
| Payout Trigger | Verified disability event | Policy loan request or death benefit |
| Capital Access | Limited to benefit amount | Flexible, based on cash value |
| Growth Component | None (pure protection) | Guaranteed cash value growth |
Disability insurance is a pure risk transfer mechanism. You pay premiums to transfer the financial risk of disability to the insurer. Privatized banking is a capital accumulation and utilization mechanism. It uses the insurance vehicle to store and leverage wealth.
Liquidity and Access to Capital
One of the most significant advantages of privatized banking is the liquidity it provides. Traditional investments, such as stocks or real estate, often require a sale or refinancing process to access capital. This can be time-consuming and may trigger tax events.
In contrast, a whole life policy provides immediate access to cash value through policy loans. This liquidity is crucial for seizing investment opportunities or covering unexpected expenses without disrupting your long-term financial plan. According to financial experts, the ability to access capital on your own terms reduces reliance on high-interest credit cards and personal loans.
For business owners, this liquidity can be the difference between maintaining cash flow during a downturn and facing insolvency. By using your private bank as collateral, you maintain control over your financial destiny.
Tax Advantages and Growth
Tax efficiency is a cornerstone of wealth preservation. Disability income protection premiums are generally not tax-deductible for individuals, though benefits received are typically tax-free. This makes it a cost-effective way to protect your tax-free income stream.
Privatized banking offers distinct tax advantages. The cash value grows tax-deferred, and policy loans are generally tax-free as long as the policy remains in force. Upon death, the death benefit is paid out income-tax-free to your beneficiaries. This makes it a powerful tool for generational wealth transfer.
Furthermore, the guaranteed growth component of whole life insurance provides stability in volatile markets. While the stock market may fluctuate, your private bank offers a predictable growth trajectory, ensuring that your capital base is not eroded by market downturns.
Synergizing Your Financial Strategy
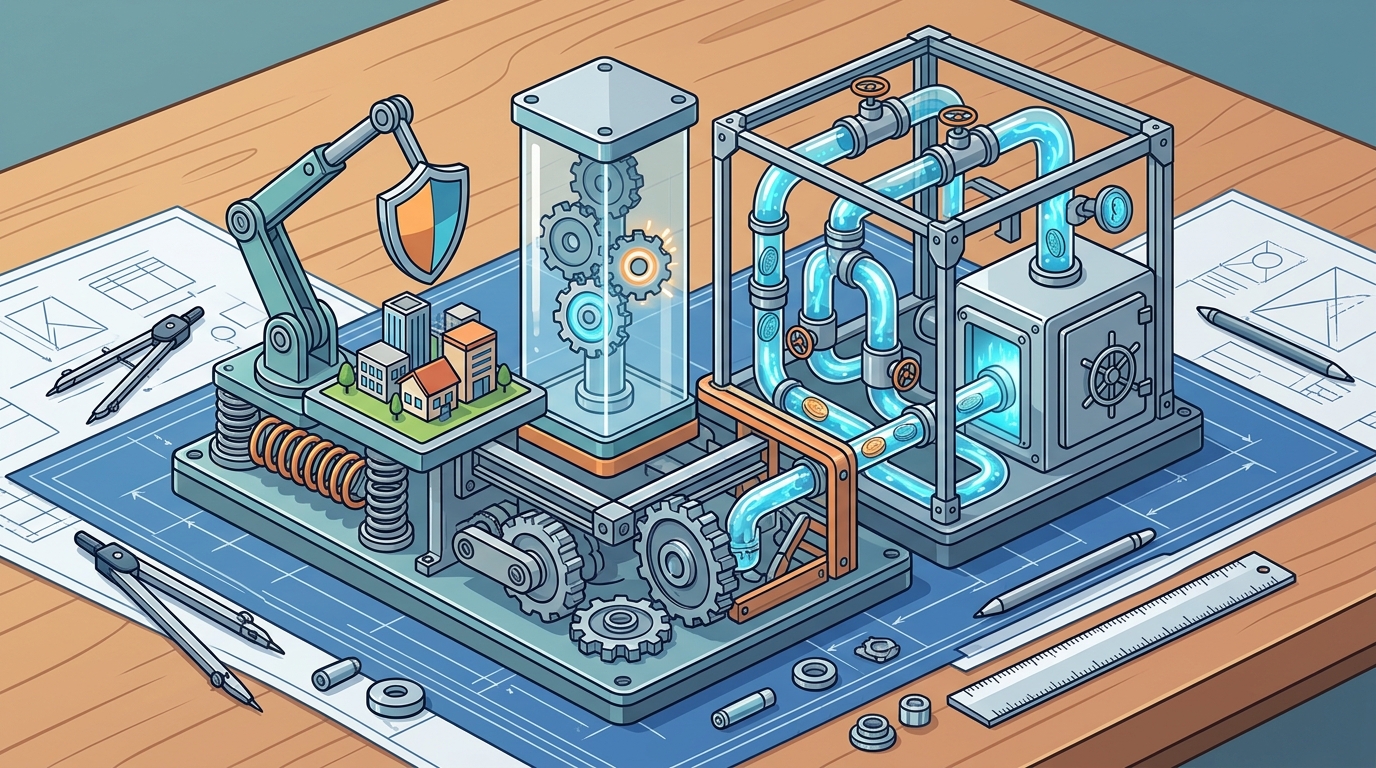
Rather than viewing these as competing options, the most successful financial plans integrate both. Disability income protection ensures that your ability to earn income remains intact. Privatized banking ensures that your income is utilized efficiently to build wealth.
For example, a business owner might use disability insurance to protect their salary while using privatized banking to finance business expansion. This dual approach creates a resilient financial structure that can withstand both personal health crises and economic shifts. We help clients design these comprehensive plans through our Retirement Planning services.
Key Takeaways
- Disability Income Protection is essential for safeguarding your earning capacity against unforeseen health events.
- Privatized Banking utilizes whole life insurance to create a personal banking system with guaranteed growth.
- Recapturing Interest through privatized banking can increase your effective savings rate by over 400%.
- Liquidity in a private bank allows for immediate access to capital without market timing risks.
- Tax Efficiency is maximized through tax-deferred growth and tax-free policy loans in whole life policies.
- Integration of both strategies provides a comprehensive shield for both income and capital.
- Professional Guidance is critical to tailor these strategies to your specific business and personal needs.
Frequently Asked Questions
Is disability income protection necessary if I have savings?
Savings can be depleted quickly during a long-term disability. Disability income protection provides a steady, predictable income stream that preserves your capital for long-term goals.
How does privatized banking differ from traditional banking?
Traditional banking lends your money to others at interest. Privatized banking allows you to borrow against your own cash value, paying interest to yourself while your cash value continues to grow.
Can I use privatized banking to pay off debt?
Yes. By using the cash value of your policy as collateral, you can pay off high-interest debt and recapture the interest payments, effectively increasing your net worth.
What is the role of whole life insurance in this strategy?
Whole life insurance provides the guaranteed cash value growth and death benefit that make privatized banking a secure and reliable financial tool.
How do I start a privatized banking strategy?
Start by consulting with a financial strategist who can design a policy tailored to your cash flow and wealth goals. Contact us to schedule a free strategy session.
Are policy loans taxable?
Generally, no. Policy loans are not considered taxable income as long as the policy remains in force. However, it is important to manage loan balances carefully to avoid policy lapse.
Schedule Your Strategy Session
Building financial independence requires a clear roadmap. Whether you need to protect your income with disability insurance or build wealth through privatized banking, the experts at Generational Wealth Concepts are here to help. We provide personalized strategies for families, business owners, and retirees.
Do not leave your financial future to chance. Take control of your wealth today. Schedule a FREE Strategy Session with Daniel Soto and his team to design a plan that sets you up for lifelong financial success.