
Retirement planning often feels like choosing between two different financial languages. One side promises guaranteed income streams, while the other offers dynamic liquidity and wealth accumulation. According to recent industry data, the average American savings rate hovers around 6%, while debt interest costs consume nearly 35% of income for many households. This disparity highlights why understanding the mechanics of your financial tools is critical. At Generational Wealth Concepts, we help families navigate these complex choices by evaluating how fixed income products stack up against privatized banking strategies. This comparison will clarify which path aligns with your specific goals for security, growth, and legacy.
Understanding Annuities for Retirement Income
Annuities are insurance contracts designed to provide a steady stream of income, typically during retirement. They act as a financial safety net, protecting you from the risk of outliving your savings. At Generational Wealth Concepts, we specialize in structuring annuity strategies that fit individual income, legacy, and risk tolerance goals. The primary value proposition of an annuity is predictability. You trade the potential for higher market returns for the certainty of a paycheck.
Types of Annuities Available
Not all annuities are created equal. Understanding the specific types is essential for making an informed decision. The most common categories include:
- Fixed Annuities: These offer steady, predictable interest rates with principal protection. They are ideal for conservative investors seeking stability.
- Fixed Indexed Annuities (FIAs): FIAs allow you to earn interest based on market index performance, such as the S&P 500, without the risk of losses during market downturns. This makes them a popular choice for those wanting upside potential with a floor.
- Income Annuities: Also known as immediate annuities, these turn a lump sum of savings into a monthly "retirement paycheck" for life.
- Hybrid Annuities with LTC Riders: These combine income generation with long-term care coverage, providing a comprehensive safety net for aging.
For more details on how these products work, you can explore our Annuities for Retirement Income page. The core benefit here is the elimination of market risk. If your primary goal is to ensure you never run out of money, annuities are a powerful tool.
The Privatized Banking Model Explained
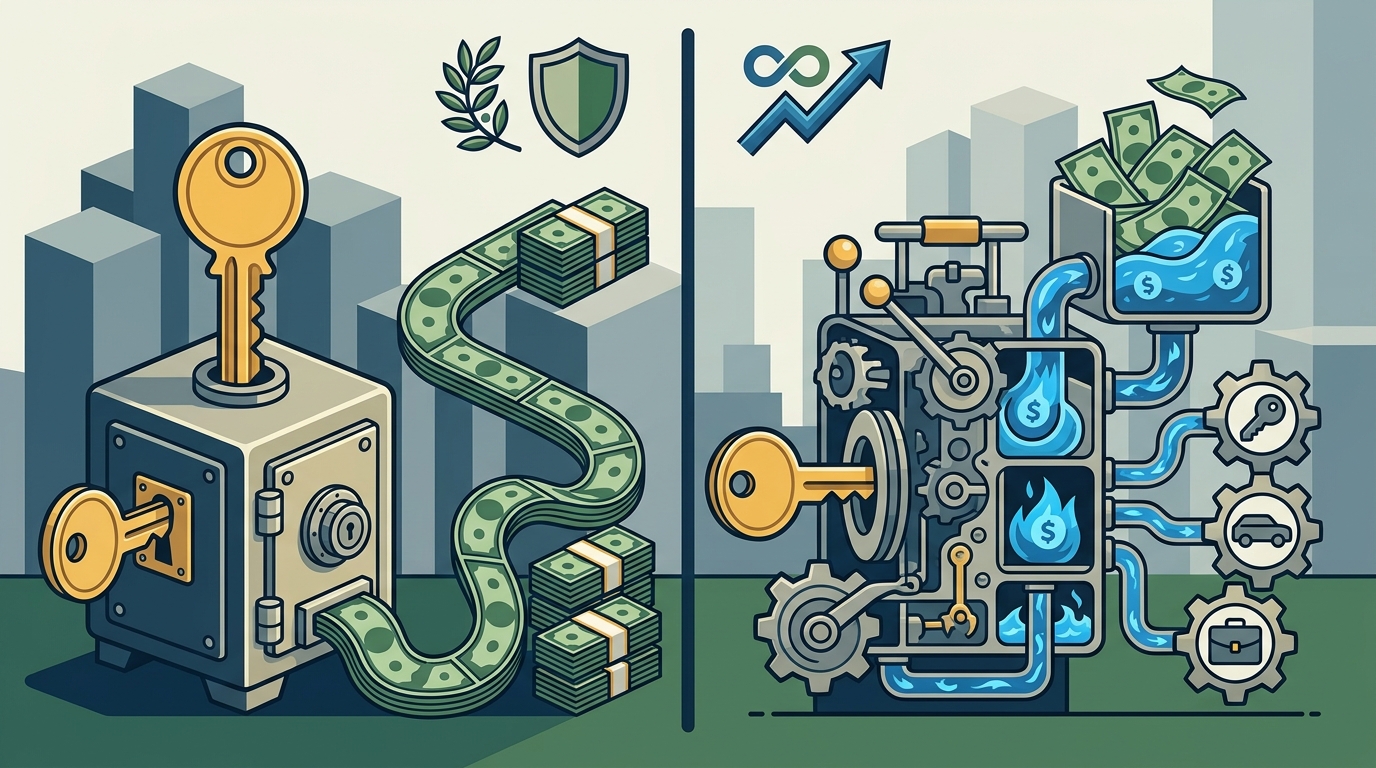
Privatized Banking, often referred to as the Infinite Banking Concept, takes a fundamentally different approach. Instead of relying on an insurance company to pay you, you become the bank. This strategy utilizes a dividend-paying whole life insurance policy engineered to maximize cash value. You then use this growing "bank" as collateral to finance your next investment or purchase.
Here is how the mechanism works in practice. You create a private bank that you control with a guaranteed growth rate. When you need capital, you take a loan against your policy. As your investment earns a return, you pay down the collateral loan. Meanwhile, your "bank" continues to grow and accrue compound interest uninterrupted. If you pay cash for your investments, you are losing the interest that your cash could have earned. Privatized Banking allows you to purchase investments without giving up the interest your "bank" is earning.
This approach is detailed further in our guide on Privatized Banking. The philosophy is simple: stop paying interest to financial institutions and start paying yourself. By recapturing your own debt, you can potentially increase your overall savings rate by over 400%. This is not just about saving; it is about creating a dynamic financial engine that works for you.
Liquidity and Access to Capital
One of the most significant differences between these two strategies is how you access your money. Annuities are designed for long-term income, not short-term liquidity. While some annuities allow withdrawals, they often come with surrender charges or tax penalties if accessed before a certain age. This lack of flexibility can be a drawback if you face unexpected financial needs.
In contrast, Privatized Banking offers superior liquidity. Because the cash value in a whole life policy grows tax-deferred and is accessible via policy loans, you have immediate access to capital. This liquidity is crucial for seizing investment opportunities or managing cash flow during economic downturns. You are not locked into a fixed schedule. You control the timing and amount of your withdrawals, provided you maintain the policy in force.
This flexibility is a key reason why many entrepreneurs and high-net-worth individuals prefer privatized banking. It allows for strategic debt recapture. By using the policy to pay off high-interest debt, you recapture the interest you were previously paying to banks. This process is outlined in our About section, where we discuss how Daniel Soto used this strategy to build his own financial independence.
Growth and Tax Advantages
Tax efficiency is a major driver in retirement planning. Both annuities and whole life insurance policies offer tax-deferred growth, but the mechanisms differ. With fixed indexed annuities, your gains are not taxed until you withdraw them. This deferral allows your money to compound faster than in a taxable account. However, withdrawals are taxed as ordinary income.
Privatized Banking offers a different tax advantage. Policy loans are generally tax-free as long as the policy remains in force. This means you can access your money without triggering a taxable event. Furthermore, the death benefit paid to your beneficiaries is typically income-tax-free. This makes privatized banking a powerful tool for legacy planning. You can pass on wealth without the erosion caused by income taxes.
For a deeper dive into the tax benefits of Fixed Indexed Annuities, read our blog post on Tax Deferral with FIAs: Grow Now, Pay Later. While annuities provide a safe harbor for growth, privatized banking provides a dynamic vehicle for wealth creation and transfer. The choice depends on whether you prioritize guaranteed income or flexible wealth accumulation.
Comparative Analysis: Key Differences
To help you decide which strategy is right for you, here is a direct comparison of the core features.
| Feature | Annuities (Fixed/Indexed) | Privatized Banking (Whole Life) |
|---|---|---|
| Primary Goal | Guaranteed lifetime income | Wealth accumulation and liquidity |
| Risk Profile | Low (Principal protected) | Low (Guaranteed growth + market upside potential) |
| Liquidity | Low (Surrender charges apply) | High (Policy loans available) |
| Tax Treatment | Tax-deferred growth; taxed as income on withdrawal | Tax-deferred growth; tax-free policy loans |
| Legacy Planning | Death benefits available | Robust legacy planning with cash value transfer |
| Best For | Conservative retirees seeking stability | Entrepreneurs and professionals seeking control |
This table highlights the trade-offs. Annuities are excellent for those who want to "set it and forget it" regarding income. Privatized banking is for those who want to actively manage their financial destiny. Both strategies can be part of a diversified plan, but they serve different roles.
Key Takeaways
- Income vs. Control: Annuities provide guaranteed income, while privatized banking provides control over capital and growth.
- Liquidity Matters: Privatized banking offers immediate access to funds via policy loans, whereas annuities often have surrender periods.
- Tax Efficiency: Policy loans in privatized banking are tax-free, offering a significant advantage over taxable annuity withdrawals.
- Debt Recapture: Using privatized banking to pay off debt can increase your savings rate by over 400% by recapturing interest payments.
- Legacy Building: Both strategies offer death benefits, but privatized banking allows for more flexible wealth transfer strategies.
- Risk Management: Fixed indexed annuities protect against market downturns, while whole life policies offer guaranteed cash value growth.
- Professional Guidance: Both strategies require careful structuring to align with your specific financial goals and risk tolerance.
Frequently Asked Questions
Can I use both annuities and privatized banking?
Yes, many clients use a hybrid approach. They may use annuities for baseline guaranteed income and privatized banking for liquidity and investment opportunities. This diversification balances security with flexibility.
Is privatized banking safe?
Privatized banking relies on whole life insurance policies, which are regulated and guaranteed by the insurance company. The cash value grows at a guaranteed rate, making it a low-risk strategy for wealth accumulation.
What is the average savings rate in America?
The average savings rate in America is currently only about 6% of earned income. Meanwhile, the average American is spending around 34.5% for interest on debt. Privatized banking aims to reverse this trend by recapturing interest payments.
How do Fixed Indexed Annuities differ from Fixed Annuities?
Fixed annuities offer a set interest rate, while Fixed Indexed Annuities (FIAs) earn interest based on a market index. FIAs offer the potential for higher returns with a floor that protects against market losses.
Who is privatized banking best for?
Privatized banking is ideal for entrepreneurs, business owners, and high-income professionals who want control over their capital, tax efficiency, and a dynamic wealth-building strategy.
Do annuities have surrender charges?
Yes, most annuities have surrender charges that decrease over time. These charges are designed to discourage early withdrawals and compensate the insurance company for the guarantees provided.
Can I access the cash value in a whole life policy?
Yes, you can access the cash value through policy loans. These loans are generally tax-free and do not require credit checks, providing significant liquidity.
Next Steps
Choosing between annuities and privatized banking is not about picking a winner. It is about selecting the right tool for your financial life. Whether you need the safety of guaranteed income or the power of dynamic liquidity, Generational Wealth Concepts can help you design a plan that works. We specialize in helping families build a financially independent lifestyle through proven strategies.
Ready to explore your options? Schedule a FREE Strategy Session with Daniel Soto. As a retired chiropractor and wealth coach, Daniel brings a unique perspective to financial planning. He has used these strategies to build and sell a multimillion-dollar practice and now helps others do the same. Contact us today to start building your legacy.