
Fixed Indexed Annuities vs. Whole Life: Retirement Income Showdown
Retirement planning requires more than just accumulation. It demands a strategy that balances growth with protection. Recent industry analysis suggests that integrated approaches combining insurance and annuities can improve retirement income outcomes compared to investment-only strategies. This comparison explores how Fixed Indexed Annuities and Whole Life Insurance function as distinct tools for building financial independence. (Meet Daniel Soto Wealth)
What Are Fixed Indexed Annuities?
A Fixed Indexed Annuity is a contract between you and an insurance company that offers interest credits based on the performance of a specific market index, such as the S&P 500. Unlike direct stock market investments, your principal is protected from direct market losses. This means that if the index drops, your account value does not decrease due to market performance. However, your gains are also capped by the contract's participation rates and caps. (Generational Wealth Concepts Retirement)
These annuities are designed for individuals who want potential growth without the stress of market volatility. They serve as a bridge between traditional savings accounts and high-risk investments. The primary goal is to provide a floor for your capital while allowing for upside potential during favorable market conditions. (Financial Education Blog Retirement)
At Generational Wealth Concepts, we evaluate these strategies based on your specific income needs, liquidity requirements, and time horizon. We help you understand how these instruments fit into a broader retirement plan that includes tax awareness and legacy goals.
Whole Life Insurance Basics
Whole Life Insurance is a form of permanent life insurance that provides coverage for your entire lifetime, provided premiums are paid. It consists of two main components: the death benefit and the cash value. The cash value grows at a guaranteed rate set by the insurer. This growth is tax-deferred and can be accessed through loans or withdrawals while you are alive.
Unlike term insurance, which expires after a set period, whole life offers lifelong protection. It also serves as a financial asset. The cash value can be used for various purposes, including funding education, supplementing retirement income, or serving as collateral for business loans. This dual nature makes it a versatile tool for wealth building and protection.
Our approach focuses on using whole life insurance as part of a privatized banking strategy. This involves leveraging the policy's cash value to create liquidity for other investments, thereby maintaining the policy's growth potential while accessing capital. This method helps clients build wealth with guarantees, aligning with our mission to help families build financial independence.
Income Generation Mechanics
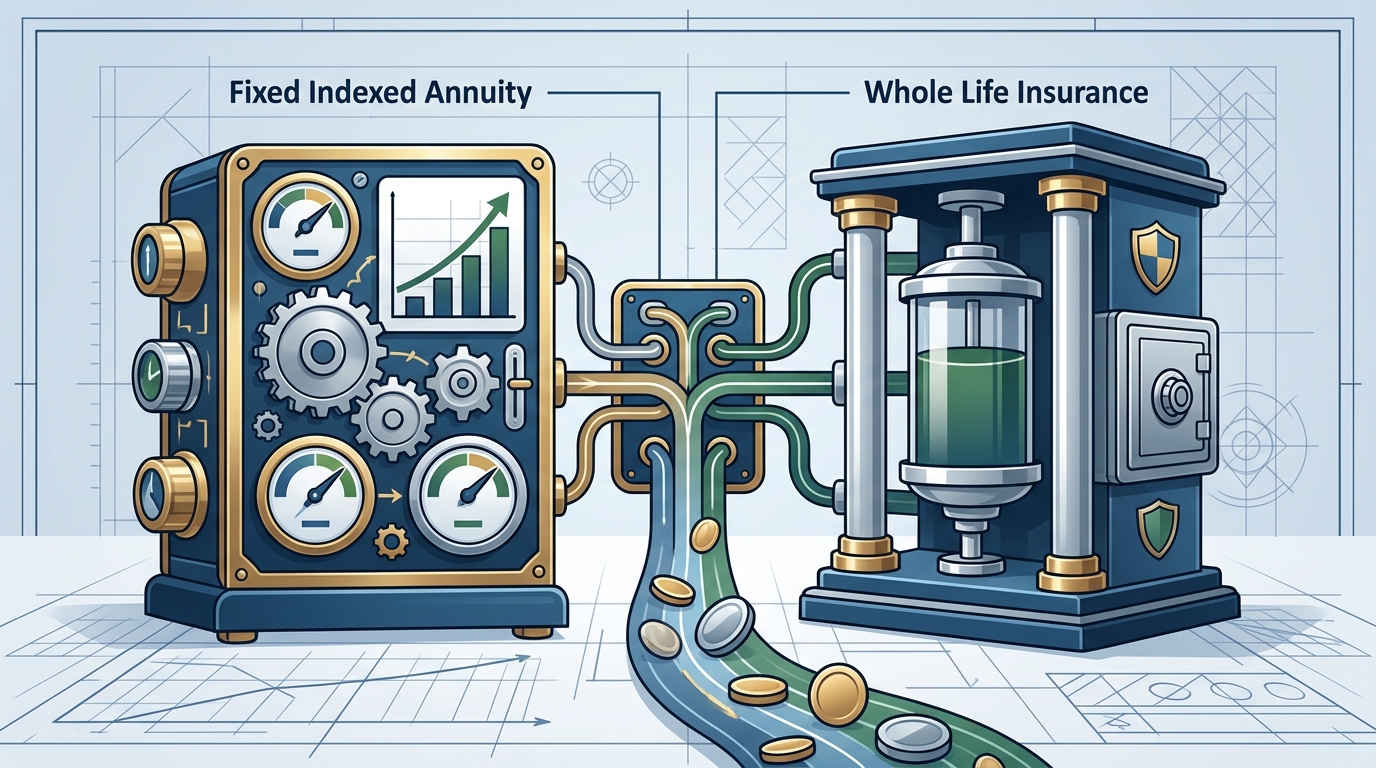
The primary difference between these two vehicles lies in how they generate income. Fixed Indexed Annuities are specifically designed to convert savings into a predictable income stream. You can choose to annuitize the contract, which means the insurance company guarantees you a monthly payment for life. This eliminates the risk of outliving your savings.
Whole Life Insurance, on the other hand, does not inherently generate income unless you take action. You must withdraw from the cash value or take policy loans to access funds. While this offers flexibility, it requires active management. If not managed correctly, excessive withdrawals can reduce the death benefit or cause the policy to lapse.
For clients seeking a "retirement paycheck" without the burden of market timing, annuities provide a structured solution. For those who prefer control over their capital and potential use of privatized banking, whole life offers a different pathway. We help you coordinate these strategies to ensure they align with your retirement income goals.
Tax Advantages and Deferral
Both Fixed Indexed Annuities and Whole Life Insurance offer significant tax benefits. Earnings in both vehicles grow tax-deferred. This means you do not pay taxes on the interest or dividends until you withdraw the money. This compounding effect can accelerate wealth accumulation over time.
However, the tax treatment of withdrawals differs. Annuity withdrawals are taxed as ordinary income. If you withdraw earnings before age 59½, you may face a 10% penalty. Whole Life Insurance loans are generally tax-free as long as the policy remains in force. This makes whole life particularly attractive for accessing capital without triggering a taxable event.
Retirement decisions can affect more than just investment balances. Roth conversions, Social Security, and Medicare IRMAA are also impacted by your income sources. We help clients understand how these pieces interact. Coordinating with tax professionals is essential to optimize your overall tax strategy.
Liquidity and Access to Funds
Liquidity refers to how easily you can access your money without penalty. Fixed Indexed Annuities often have surrender periods. If you withdraw money during this period, you may face surrender charges that decrease over time. This makes annuities less suitable for short-term needs. They are designed for long-term planning.
Whole Life Insurance offers more flexible access to cash value. You can take loans against your policy at any time. These loans do not require credit checks or approval from the insurance company. However, unpaid loans plus interest will reduce the death benefit. This flexibility is a key component of the privatized banking strategy we promote.
Understanding liquidity is crucial for retirement planning. You need access to funds for emergencies and opportunities. We help you balance the need for guaranteed income with the need for accessible capital. This balance is vital for maintaining financial independence throughout your retirement years.
Legacy and Estate Planning
Legacy planning involves passing wealth to your heirs efficiently. Whole Life Insurance is often preferred for this purpose. The death benefit is paid directly to beneficiaries, typically income-tax-free. It bypasses probate, ensuring a quick and private transfer of assets. This makes it an effective tool for estate liquidity.
Fixed Indexed Annuities can also leave a legacy, but the process may be more complex. Some annuities offer death benefit riders that guarantee a minimum payout to beneficiaries. However, the payout may be subject to taxes depending on the type of account and the beneficiary's status. We coordinate with estate planning attorneys to ensure your legacy goals are met.
A strong retirement strategy considers the risks that can disrupt a family's plan. We help evaluate life insurance and long-term care strategies designed to protect income and assets. For legacy goals, we coordinate insurance strategies with your attorney and tax professional. This ensures all pieces of your plan work together seamlessly.
Key Takeaways
- Principal Protection: Fixed Indexed Annuities protect your principal from direct market losses, while whole life cash value grows at a guaranteed rate.
- Income Predictability: Annuities can provide contractually guaranteed lifetime income, eliminating longevity risk.
- Tax Efficiency: Both vehicles offer tax-deferred growth, but whole life loans offer tax-free access to capital.
- Liquidity: Whole life insurance generally offers more flexible access to cash value than annuities with surrender periods.
- Legacy Goals: Whole life death benefits are typically income-tax-free and bypass probate, making them efficient for estate planning.
- Strategic Use: Integrating both can improve retirement income and legacy outcomes compared to using either alone.
- Professional Coordination: Successful implementation requires coordination with tax and legal professionals for comprehensive planning.
Frequently Asked Questions
Are Fixed Indexed Annuities safe?
Fixed Indexed Annuities offer principal protection from direct market losses. However, they are subject to the claims-paying ability of the issuing insurance company. They are not FDIC insured, but they provide a floor for your investment.
Can I access my Whole Life Insurance cash value?
Yes, you can access your cash value through policy loans or withdrawals. Loans are generally tax-free as long as the policy remains in force. Withdrawals may reduce the death benefit and could have tax implications if they exceed your basis.
Which is better for retirement income?
Fixed Indexed Annuities are specifically designed to generate predictable income. Whole Life Insurance can supplement income but requires active management. The best choice depends on your need for guaranteed paychecks versus flexible access to capital.
Do I need both an annuity and life insurance?
Many clients benefit from a combination. Annuities provide income security, while life insurance provides protection and liquidity. Integrated approaches can improve overall retirement outcomes by balancing growth, income, and legacy goals.
How does privatized banking work with whole life?
Privatized banking uses a whole life policy as collateral to finance investments. This allows you to access capital without surrendering the policy. Your cash value continues to grow while you use the loan for other purposes, creating a dynamic financial strategy.
What are the tax implications of annuity withdrawals?
Annuity withdrawals are taxed as ordinary income. Earnings are taxed first, followed by contributions. Withdrawals before age 59½ may incur a 10% penalty. Proper planning can help minimize these tax impacts.
How do I choose the right strategy?
Consider your income needs, risk tolerance, and legacy goals. We help evaluate your specific circumstances to determine the appropriate mix of annuities and insurance. A personalized strategy review is the best first step.
Schedule Your Strategy Review
Building financial independence requires a coordinated approach. Whether you are interested in Fixed Indexed Annuities, Whole Life Insurance, or a combination of both, we are here to help. At Generational Wealth Concepts, we focus on helping clients make informed decisions based on their goals. We do not rely on a one-size-fits-all approach.
Contact us to schedule a free strategy session. We will help you understand how these tools can work together to protect your income, build wealth, and secure your legacy. Visit our appointment page to get started. You can also reach us at contact for more information.