
Securing a reliable retirement income stream is the primary financial goal for millions of Americans approaching their golden years. The average savings rate in America is currently only about 6% of earned income, a figure that highlights the urgency of creating alternative wealth-building vehicles financial experts note. Without strategic intervention, retirees face the risk of outliving their assets or relying heavily on volatile market performance. This guide explores two powerful, non-traditional approaches to retirement security: fixed indexed annuities and the privatized banking strategy. By understanding these mechanisms, you can build a financial foundation that prioritizes safety, guaranteed growth, and legacy preservation.
What is Privatized Banking?
Privatized banking is a financial strategy that utilizes a dividend-paying whole life insurance policy to create a personal "bank" that you control. This concept allows individuals to leverage the cash value of their policy as collateral for loans, rather than liquidating assets or taking on high-interest debt. The core mechanism relies on the policy's ability to grow tax-deferred while simultaneously providing liquidity for major purchases or investments.
At its foundation, Privatized Banking is a method of recapturing interest that would otherwise be paid to traditional financial institutions. By using your own growing cash value to finance your needs, you keep the interest within your own financial ecosystem. This approach is particularly effective for business owners and high-income professionals who need flexible access to capital without disrupting their long-term wealth accumulation plans. For more details on how this strategy supports business owners, visit our insurance services page.
How Privatized Banking Works for Retirement
The process begins with the establishment of a "Private Bank" through a custom-tailored whole life insurance policy. This policy is engineered to maximize cash value growth while maintaining a guaranteed growth rate. Once the policy is funded, it serves as a secure asset that can be used to finance your next investment or major purchase.
When you take a loan against your policy, you do not trigger a taxable event. Instead, you pay interest back to your own policy, effectively paying yourself. Meanwhile, your "bank" continues to grow and accrue compound interest uninterrupted. This is a critical distinction from traditional financing, where interest payments are lost to external lenders. If you pay cash for your investments, you are losing the interest that your cash could have earned when you make an investment. Privatized Banking allows you to purchase investments without giving up the interest your "bank" is earning.
This strategy is not just about borrowing; it is about creating a self-sustaining financial engine. By recapturing your own debt and paying yourself the interest that you are currently paying others, you could increase your overall savings rate by over 400%. This compounding effect is the same force the wealthy use to build generational wealth wealth coaches emphasize.
Types of Annuities for Retirement Income
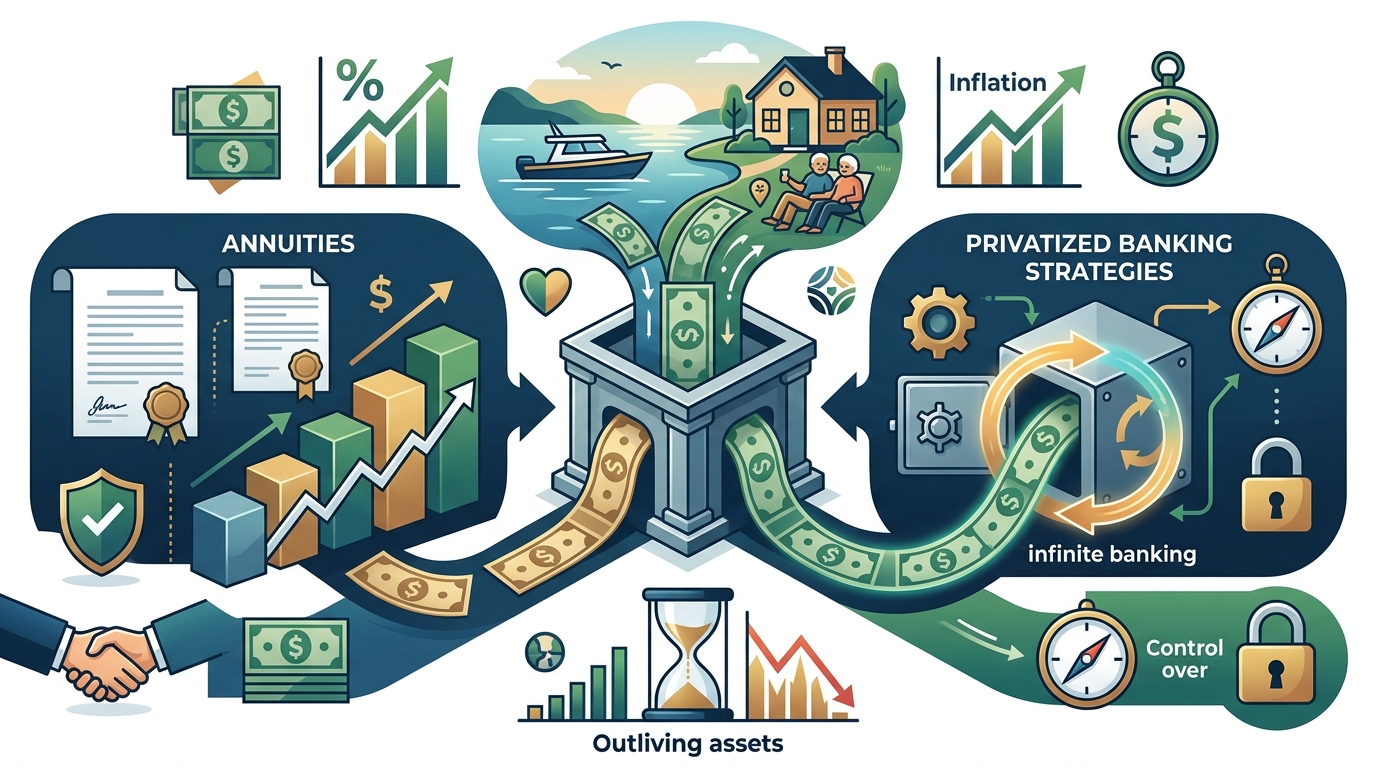
While privatized banking focuses on liquidity and leverage, annuities provide the bedrock of guaranteed retirement income. Annuities are designed to protect your principal while ensuring you never outlive your savings. At Generational Wealth Concepts, we design annuity strategies that fit your income, legacy, and risk tolerance goals.
Fixed Annuities
Fixed annuities offer steady, predictable interest rates with principal protection. They are ideal for conservative investors who prioritize stability over market participation. The insurance company guarantees the interest rate for a specific period, providing a safe harbor for your retirement savings.
Fixed Indexed Annuities (FIAs)
Fixed Indexed Annuities allow you to earn interest based on market index performance, such as the S&P 500, without direct exposure to market risk. If the index performs well, your account grows. If the index performs poorly, your principal remains protected from losses. This makes FIAs a powerful tool for tax-deferred growth with downside protection.
Income Annuities
Income annuities, also known as immediate annuities, turn a portion of your savings into a monthly "retirement paycheck" for life. This option eliminates the fear of outliving your money by providing a guaranteed stream of income regardless of market conditions or longevity.
Hybrid Annuities with LTC Riders
Hybrid annuities combine income features with long-term care coverage. This is particularly relevant for retirees concerned about the high cost of elder care. By adding a long-term care rider, you can access your death benefit if you need care, ensuring your legacy is preserved for heirs if you do not.
FIAs vs. The Stock Market
One of the most common questions in retirement planning is whether to invest in the stock market or use annuities. The stock market offers high growth potential but comes with significant volatility. A downturn in your retirement years can devastate your portfolio, a phenomenon known as sequence of returns risk.
Fixed Indexed Annuities offer a safer path to growth by capping your downside risk. While you may not capture the full upside of a bull market, you are protected from the catastrophic losses that can occur during bear markets. This balance of growth and safety is why many financial planners recommend a portion of retirement assets be allocated to annuities. For a deeper dive into tax deferral strategies with FIAs, read our blog post on tax deferral.
According to industry data, the average American is spending around 34.5% for interest on debt. By shifting some of your financial strategy toward guaranteed income vehicles and privatized banking, you can reduce this burden and redirect those funds toward your retirement security. This shift is critical for building a resilient financial plan that can withstand economic fluctuations.
Debt Recapture and Cash Flow
Being in debt can be such a horrible feeling. Yet paying off debt seems like such a hard thing for many. The average savings rate in America is currently only about 6% of earned income. Meanwhile, the average American is spending around 34.5% for interest on debt. This disparity highlights the inefficiency of traditional debt management.
By using Privatized Banking to pay off all your debts, you can recapture the interest that you are currently paying financial institutions. At the core of Privatized Banking is a dividend paying permanent life insurance policy which is used to create a BANK that you control. This policy is engineered to MAXIMIZE CASH VALUE even while you are using it for your personal financing. By recapturing your own debt and paying yourself the interest that you are currently paying others, you could increase your overall savings rate by over 400%.
This strategy is not just for debt elimination. It is also for wealth creation. Privatized Banking allows you to create wealth and pass it on for generations to come. Here’s how it works: create a "Private Bank" that you control and is guaranteed to grow. Privatized Banking uses a (custom to your needs) dividend paying, whole life insurance policy to create this "BANK" then uses this growing "BANK" as collateral to finance your family’s purchases. As the money is paid back, you pay down the collateral loan on your "BANK". Meanwhile, your "BANK" continues to grow and accrue compound interest uninterrupted.
Key Takeaways
- Privatized Banking uses whole life insurance cash value as collateral, allowing you to finance investments while your money continues to grow.
- Fixed Indexed Annuities provide market-linked growth with principal protection, eliminating the risk of loss during market downturns.
- Debt Recapture is a core benefit of privatized banking, potentially increasing your savings rate by over 400% by paying interest to yourself.
- Guaranteed Lifetime Income through income annuities ensures you never outlive your retirement savings, regardless of market performance.
- Tax Deferral allows your annuity earnings to grow without immediate tax liability, compounding your wealth faster than taxable accounts.
- Legacy Preservation is enhanced through hybrid annuities and life insurance, ensuring your heirs receive benefits even if you need long-term care.
- Financial Independence is achieved by combining these tools to create a self-sustaining financial ecosystem that operates independently of traditional banking.
Frequently Asked Questions
What is the difference between a fixed annuity and a fixed indexed annuity?
A fixed annuity offers a guaranteed interest rate set by the insurance company, providing predictable growth. A fixed indexed annuity (FIA) ties its interest earnings to a market index, such as the S&P 500, allowing for potential higher returns while still protecting your principal from market losses.
How does privatized banking help with retirement income?
Privatized banking creates a personal "bank" through a whole life policy. You can borrow against this cash value to fund retirement projects or pay off debt, while the policy continues to grow tax-deferred. This allows you to recapture interest and build wealth simultaneously.
Are annuities a good investment for retirees?
Annuities are often recommended for retirees seeking guaranteed income and principal protection. They eliminate the risk of outliving your savings and provide a stable financial floor, complementing other investments like stocks or real estate.
Can I use privatized banking to pay off my mortgage?
Yes, many clients use privatized banking to finance their homes. By using the policy as collateral, you can access funds at competitive rates while your cash value continues to grow. This strategy can also help you recapture the interest you would otherwise pay to a bank.
What is the average savings rate in America?
The average savings rate in America is currently only about 6% of earned income. This low rate highlights the importance of strategic financial planning to build wealth and secure retirement.
Do I need to pay taxes on annuity withdrawals?
Annuity earnings grow tax-deferred. You only pay taxes when you withdraw the earnings. If you withdraw more than your basis (the amount you contributed), the earnings portion is taxed as ordinary income. However, loans against a whole life policy used for privatized banking are generally not taxable.
How does Generational Wealth Concepts help with retirement planning?
We provide comprehensive financial education and implementation of privatized banking and annuity strategies. Our team helps individuals, business owners, and professionals build protection, safety, and stability into their financial cash flow through customized whole life insurance and annuity plans.
Schedule Your Strategy Session
Retirement planning is not a one-size-fits-all endeavor. Whether you are interested in the liquidity of privatized banking or the security of annuities, the right strategy depends on your unique financial situation. At Generational Wealth Concepts, we help families build a financially independent lifestyle through proven tools and education.
If you are feeling unsure where to start with the infinite banking concept or annuity planning, contact us to set up a private consultation. We are in the business of helping people like you achieve financial independence through our tried and true tool, Private Family Financing. Schedule a FREE Strategy Session today to explore how these strategies can work for you.