
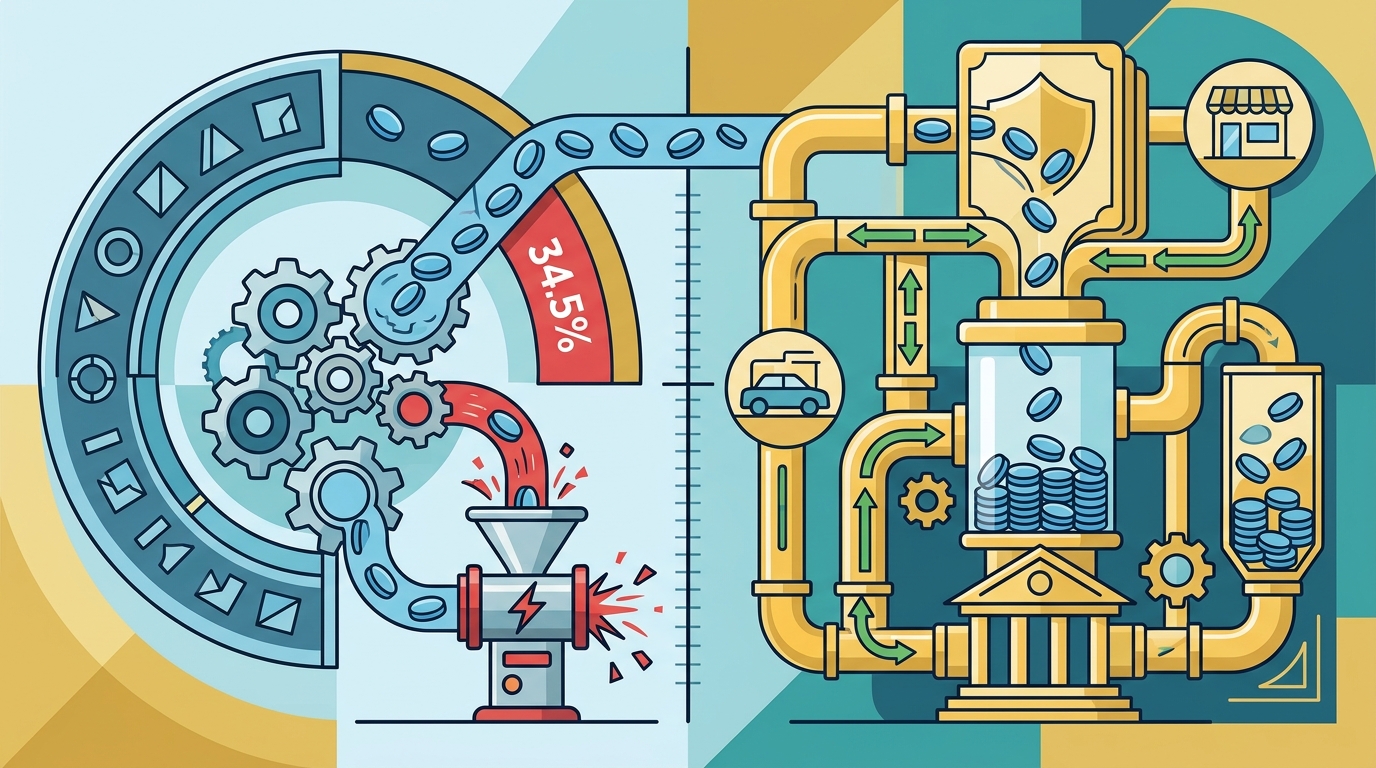
The average American is spending around 34.5% of their income on interest payments to financial institutions. This statistic highlights a critical inefficiency in modern personal finance where capital is drained rather than accumulated. By understanding the mechanics of privatized banking, individuals can shift from being debt consumers to capital creators. This analysis explores how leveraging whole life insurance policies can recapture interest and build generational wealth.
What is Privatized Banking?
Privatized Banking is a financial strategy that utilizes a dividend-paying whole life insurance policy to create a private source of capital. This method allows individuals to borrow against their cash value at competitive rates while their principal continues to grow tax-deferred. Unlike traditional banking where deposits earn minimal interest, this approach maximizes the utility of your capital.
At Generational Wealth Concepts, we teach families how to be the bank for their own financial needs. This concept is not about eliminating debt but rather about changing the recipient of the interest payments. By using your policy as collateral, you pay interest to yourself instead of a bank. This creates a closed-loop financial system that preserves wealth.
The foundation of this strategy relies on the insurance services provided by high-quality carriers. These policies are engineered to maximize cash value accumulation. This growth is guaranteed and protected from market volatility, providing a stable foundation for your financial portfolio.
The Debt Recapture Mechanism
Most individuals view debt as a necessary evil. However, the cost of that debt is often overlooked in standard financial planning. The average savings rate in America is currently only about 6% of earned income. Meanwhile, the average American is spending around 34.5% for interest on debt. This disparity represents a massive leak in household wealth.
By using Privatized Banking to pay off all your debts, you can recapture the interest that you are currently paying financial institutions. This process is known as debt recapture. You replace high-interest consumer debt with low-interest policy loans. The difference between the interest you pay on the loan and the interest your policy earns becomes your new savings rate.
Consider the following scenario. You have a $50,000 car loan at 7% interest. In a traditional model, you pay $3,500 annually in interest to a bank. With privatized banking, you borrow against your policy at a lower rate, say 5%. Your policy continues to earn dividends on the full $50,000. You are now earning interest on money you are also using. This dual-earning potential is the core benefit of this strategy.
By recapturing your own debt and paying yourself the interest that you are currently paying others, you could increase your overall savings rate by over 400%. This is not a theoretical gain but a mathematical certainty based on the structure of the policy. For more details on how this works, review our guide on how privatized banking works.
Comparing Financial Tools
When conducting a cost-benefit analysis, it is essential to compare the available options. Traditional banking relies on the spread between what they pay depositors and what they charge borrowers. Privatized banking eliminates this spread for the individual.
| Feature | Traditional Banking | Privatized Banking |
|---|---|---|
| Interest Paid on Debt | High (Market Rates) | Low (Policy Loan Rate) |
| Interest Earned on Capital | Minimal (Savings Accounts) | Guaranteed Dividends |
| Market Risk | High (Investment Portfolios) | None (Guaranteed Growth) |
| Legacy Benefit | Zero (Debt is Paid Off) | Death Benefit for Heirs |
| Tax Implications | Taxable Interest Income | Tax-Deferred Growth |
The table above illustrates the structural advantages of privatized banking. Traditional banking extracts value from your life. Privatized banking retains value within your family unit. This is particularly important for business owners who need reliable access to capital without liquidating assets.
Another critical component is the protection of your income. Disability insurance ensures that your ability to fund your policy remains intact even if you cannot work. This synergy between protection and growth is unique to the insurance ecosystem.
Long-Term Wealth Building
Compounding interest is the most powerful force in finance. The wealthy understand that they must do what the wealthy do. This means allowing capital to work harder than labor. Privatized banking accelerates this process by ensuring that every dollar you borrow continues to earn dividends.
When you use cash to buy an asset, you lose the interest that cash could have earned. Privatized banking allows you to purchase investments without giving up the interest your bank is earning. This is the essence of generational wealth concepts. You are not just building wealth for yourself but creating a legacy for your descendants.
For retirement planning, annuities provide guaranteed income. However, privatized banking offers liquidity and flexibility that annuities often lack. You can access your cash value tax-free through loans. This makes it a superior tool for managing cash flow during retirement.
Furthermore, mortgage protection insurance can be integrated into this strategy. By using your policy to secure your home loan, you protect your family's residence while building equity. This holistic approach to finance ensures that all your assets are working in unison.
Key Takeaways
- Recapture Interest: You can increase your savings rate by over 400% by recapturing the interest you currently pay to banks.
- Guaranteed Growth: Privatized banking uses dividend-paying whole life policies to create a private bank with guaranteed growth.
- Market Protection: Your capital is protected from stock market downturns, ensuring stable wealth accumulation.
- Legacy Planning: The strategy allows you to create and pass on wealth for generations to come.
- Tax Efficiency: Cash value grows tax-deferred, and loans are generally tax-free.
- Professional Guidance: Working with a wealth coach like Daniel Soto ensures proper policy structuring.
- Debt Management: Privatized banking is a tool for managing debt, not just eliminating it.
Frequently Asked Questions
Is privatized banking safe?
Yes, privatized banking relies on whole life insurance policies which are regulated and guaranteed by the insurance carrier. The growth is contractually guaranteed, providing a safe harbor for your capital.
How does privatized banking differ from traditional banking?
Traditional banking pays you little on deposits and charges you high rates on loans. Privatized banking allows you to earn dividends on your collateral while borrowing at lower rates, effectively paying yourself interest.
Can I use privatized banking for business?
Absolutely. Many business owners use this strategy to finance equipment, real estate, or operational costs without disrupting their personal cash flow.
What is the role of Daniel Soto in this process?
Daniel Soto is a retired chiropractor and wealth coach who specializes in implementing these strategies. He helps clients design plans that fit their specific income and legacy goals.
Does this strategy work for retirees?
Yes. Retirees can use privatized banking to supplement their income, manage tax liabilities, and protect their estate from market volatility.
How do I get started?
You can start by scheduling a free strategy session to discuss your financial goals and see if this approach aligns with your needs.
What are the costs involved?
The costs include policy premiums and loan interest. However, the net benefit is often positive due to the spread between what you earn and what you pay.
Schedule Your Strategy Session
Take control of your financial future today. Do not let another year of interest payments drain your wealth. Contact Generational Wealth Concepts to learn how you can build your own private bank. Schedule a free strategy session with Daniel Soto to explore your options.