Privatized banking is a wealth strategy that uses a properly structured permanent life insurance policy to combine life insurance protection with access to policy cash value. Premium funding requirements depend on your age, health, income goals, and the specific policy design. At Generational Wealth Concepts, we help clients determine the right funding level to build a reliable source of liquidity and financial flexibility without overfunding or underfunding the strategy.
Defining the Strategy and Funding Needs
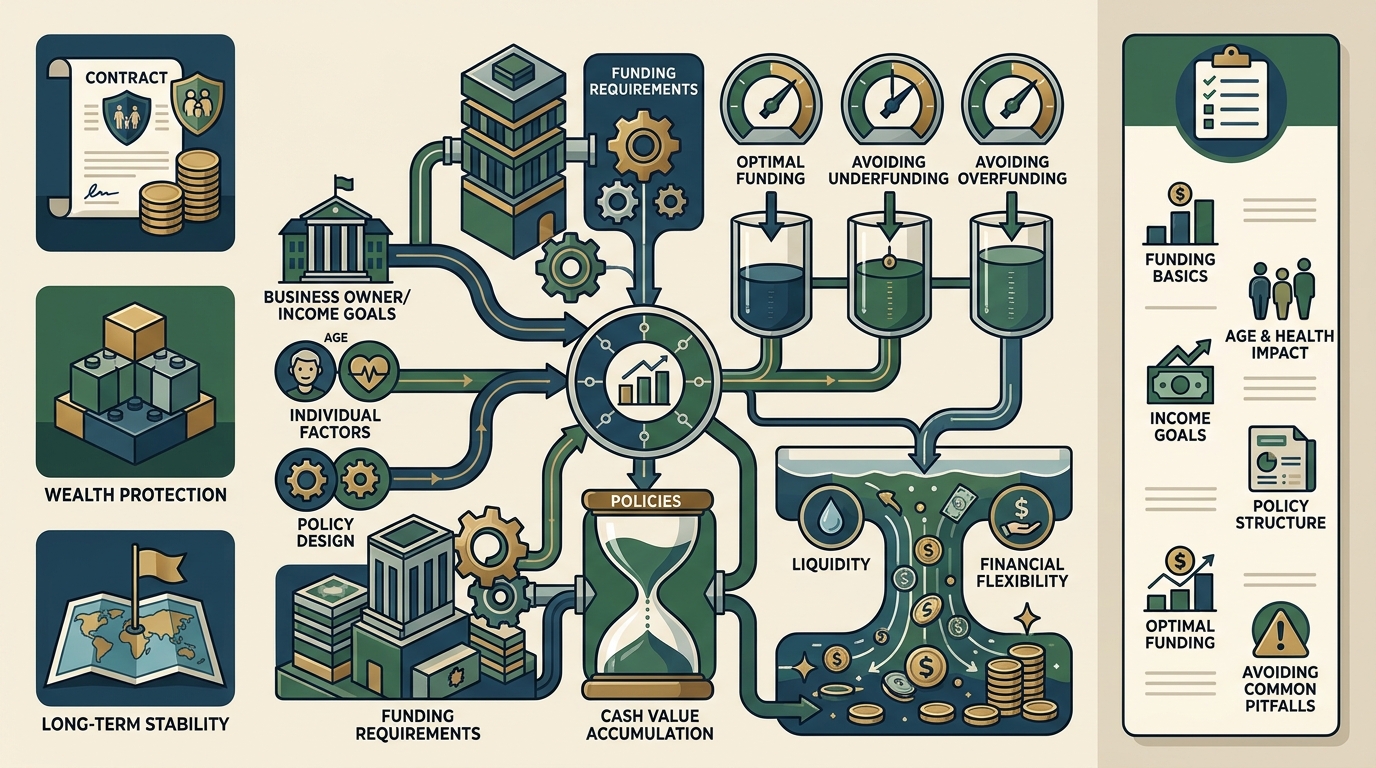
Privatized banking is not a one-size-fits-all product. It is a customized approach where the policy is designed to accumulate cash value over time. The premium funding requirement is the amount you must pay to achieve the desired cash value growth and income potential. This amount varies significantly based on the carrier, the policy type, and your personal financial goals. Understanding these variables is the first step in preparing your budget.
Key Components of Funding
The funding requirement typically includes the initial premium, the duration of payments, and the total cost of the policy. For example, a client in their 40s may require a higher annual premium than a client in their 50s to reach the same cash value target by age 65. This difference is due to the shorter accumulation period and higher mortality costs associated with older applicants.
Age and Health Impact on Premiums
Your age and health status are the primary drivers of your premium funding requirements. Insurance carriers use underwriting to assess risk, which directly affects the cost of the policy. A healthier applicant at a younger age will generally pay lower premiums for the same coverage amount. This is why early planning is critical for privatized banking strategies.
The Cost of Waiting
Policy Design and Cash Value Growth
Minimum Funding Thresholds
Each policy has a minimum premium requirement to remain active. If you pay less than this amount, the policy may lapse. At Generational Wealth Concepts, we analyze your cash flow to ensure your premium funding is sustainable over the long term. We help you balance the need for high cash value growth with the reality of your current income and expenses.
Liquidity and Access to Cash Value
Strategic Withdrawals
Strategic withdrawals or loans can provide tax-advantaged access to funds, but they must be managed carefully to avoid policy lapse. The funding requirement should account for the fact that you may need to make additional premium payments if you take out loans. This ensures the policy remains in good standing and continues to grow.
Long-Term Sustainability and Inflation
Privatized banking is a long-term strategy, often spanning 20 to 30 years or more. Your premium funding requirements must be sustainable over this entire period. Inflation and changes in your financial situation can impact your ability to maintain the same premium level. It is important to build a funding plan that accounts for these variables. For example, if your income increases, you may choose to increase your premium to accelerate cash value growth.
Reviewing Your Plan
Regular reviews are essential to ensure your premium funding remains aligned with your goals. At Generational Wealth Concepts, we recommend annual reviews of your policy performance and funding levels. This allows you to adjust your strategy as needed, ensuring that your privatized banking plan continues to meet your evolving financial needs.
Key Takeaways
- Privatized banking is a strategy that uses permanent life insurance to build cash value for liquidity and income.
- Premium funding requirements depend on age, health, policy type, and desired cash value goals.
- Younger, healthier applicants typically pay lower premiums for the same coverage.
- Policy design affects how premiums are allocated between cost of insurance and cash value growth.
- Liquidity access is tied to the amount of cash value accumulated, which depends on premium funding.
- Long-term sustainability requires a funding plan that accounts for inflation and income changes.
- Regular reviews help ensure your premium funding remains aligned with your financial goals.
Frequently Asked Questions
How much should I budget for privatized banking premiums?
Your budget depends on your age, health, and goals. A general rule is to allocate a portion of your discretionary income that you can sustain over 20+ years. We can help you determine the right amount based on your specific situation.
Can I change my premium amount after the policy is issued?
Yes, most permanent life insurance policies allow you to adjust your premium within certain limits. However, reducing premiums too much can cause the policy to lapse, while increasing them can accelerate cash value growth.
What happens if I stop paying premiums?
If you stop paying premiums, the policy will eventually lapse. You may be able to use the cash value to pay premiums for a short time, but this is not a long-term solution. It is important to maintain a sustainable funding plan.
Is privatized banking suitable for everyone?
No, it is not suitable for everyone. It works best for individuals with a long time horizon, stable income, and a need for liquidity and tax-advantaged growth. We can help you determine if it fits your financial profile.
How does privatized banking differ from a regular life insurance policy?
Privatized banking focuses on maximizing cash value accumulation for liquidity and income, whereas a regular life insurance policy may prioritize death benefit coverage. The funding requirements and policy design differ accordingly.
Can I use the cash value for business expenses?
Yes, you can use policy loans or withdrawals to fund business expenses. This can provide a tax-advantaged source of capital, but it must be managed carefully to avoid policy lapse.
Next Steps for Your Strategy
Understanding your premium funding requirements is the foundation of a successful privatized banking strategy. By considering your age, health, policy design, and long-term goals, you can create a plan that provides the liquidity and financial flexibility you need. At Generational Wealth Concepts, we are here to guide you through this process, ensuring your strategy is tailored to your unique circumstances. To begin, for a personalized review of your options.