Asset management fees in privatized banking are typically low or nonexistent because the strategy relies on insurance contracts rather than third-party portfolio managers. This structure allows individuals to retain more of their capital for growth and income generation. Generational Wealth Concepts helps clients understand how these fee structures impact long-term wealth preservation and cash flow stability.
Defining the Cost Structure
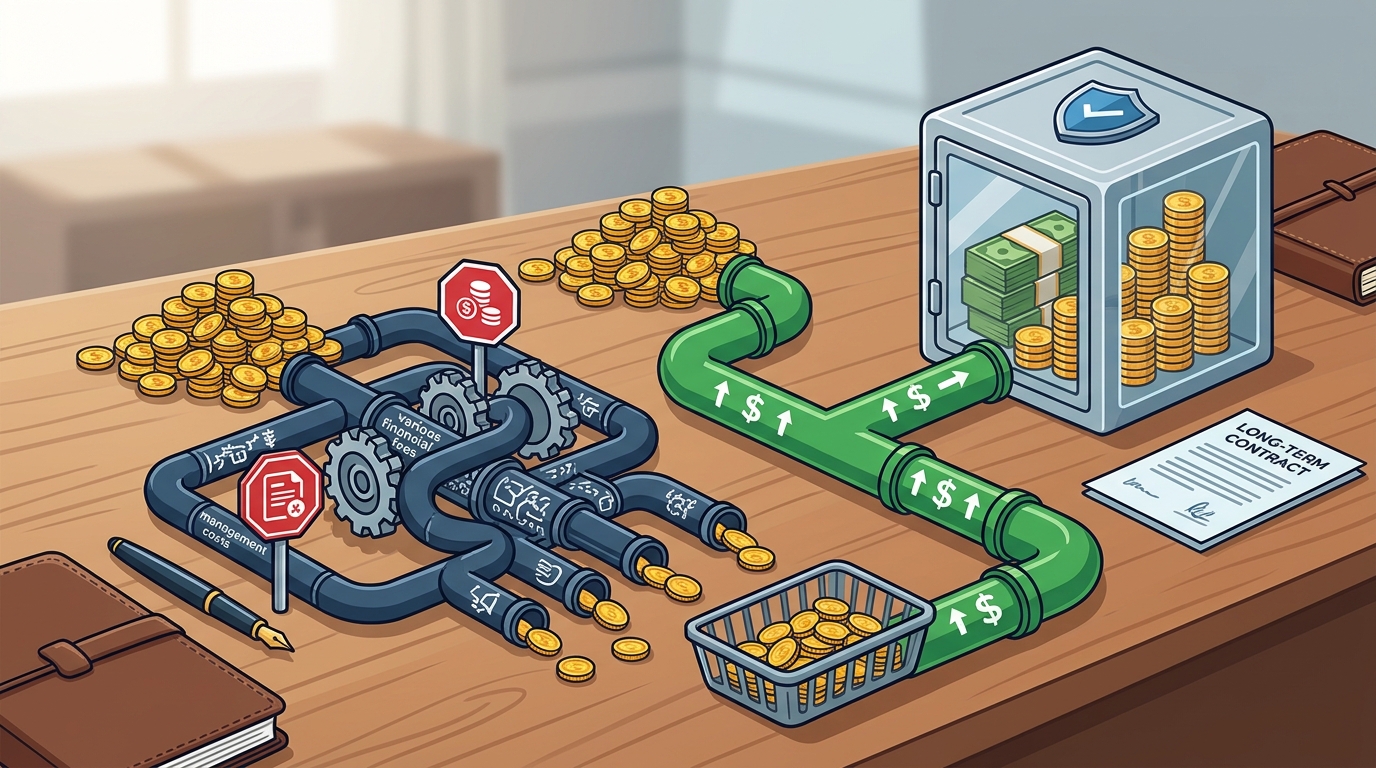
Asset management fee is a charge levied by a third-party firm for managing a client's investment portfolio. In traditional brokerage or advisory accounts, this fee is often calculated as a percentage of assets under management. In contrast, privatized banking strategies utilize permanent life insurance contracts, which generally do not carry ongoing third-party management fees. Instead, costs are embedded in the insurance product itself, such as cost of insurance and administrative charges. For additional details, review the .
Traditional vs. Privatized Fee Models
Identifying Hidden Costs
Impact on Total Strategy Costs
The total cost of a privatized banking strategy is primarily driven by the premium paid and the insurance costs. Because there are no ongoing asset management fees, the net cost is often lower than traditional managed portfolios. This allows for a higher allocation to cash value growth. Clients should compare the total cost of ownership, including all fees and charges, to evaluate the efficiency of the strategy. For additional details, review the Customer Experience.
Strategic Planning Considerations
When planning a privatized banking strategy, consider the long-term fee structure and its impact on liquidity. Generational Wealth Concepts coordinates with specialized professionals to ensure the strategy fits within the broader financial picture. Understanding how fees affect total costs helps clients make informed decisions about their retirement income and legacy planning. For additional details, review the Frequently Asked Questions.
Key Takeaways
- Asset management fees are typically absent in privatized banking strategies.
- Traditional accounts often charge 1% to 2% annually, which can erode growth.
- Privatized banking costs are embedded in insurance premiums and administrative charges.
- Reviewing policy illustrations is essential to understand total costs.
- Generational Wealth Concepts helps clients evaluate fee structures for long-term stability.
Frequently Asked Questions
Do privatized banking strategies have asset management fees?
No, privatized banking strategies generally do not have third-party asset management fees. Costs are embedded in the insurance contract.
How do insurance costs compare to management fees?
Insurance costs are typically lower than traditional management fees, especially over long time horizons.
What are the main costs in a privatized banking strategy?
The main costs include premiums, cost of insurance, and administrative fees.
Can I avoid surrender charges in privatized banking?
Surrender charges apply if funds are withdrawn early. Holding the policy long-term avoids these charges.
How does Generational Wealth Concepts help with fee analysis?
Generational Wealth Concepts reviews policy illustrations to ensure clients understand all costs involved.
Conclusion
Understanding asset management fees is crucial for evaluating the total cost of a privatized banking strategy. By avoiding third-party management fees, clients can retain more capital for growth and income. Generational Wealth Concepts provides expert guidance to help you navigate these costs and build a sustainable financial future. Schedule a strategy review to discuss your specific needs.