Families should look for an advisor who specializes in retirement income and insurance protection, not just general wealth management. The right professional focuses on creating sustainable income streams and protecting assets from unexpected risks. They must understand how insurance products like annuities and life insurance integrate with your broader financial goals. This specialized approach ensures your plan addresses both growth and security. For additional details, review the retirement.
Specialization in Retirement Income and Protection
Generalists often lack the depth required for complex retirement and insurance strategies. A dedicated advisor focuses specifically on how to generate reliable income during retirement. They understand the nuances of fixed and indexed annuities, which provide principal protection and growth potential. This specialization is critical because retirement income planning is distinct from investment management. It requires a focus on cash flow stability rather than just asset appreciation.
The Role of Annuities in Income Planning
Annuity is a contract with an insurance company that provides a stream of payments over time. These products are designed to mitigate the risk of outliving your savings. An advisor who understands annuities can help you structure a portfolio that balances guaranteed income with growth opportunities. They can explain the differences between immediate and deferred annuities, helping you choose the right timing for your needs.
Understanding Risk Management and Insurance Products
Retirement is not just about accumulating assets; it is about protecting them. A qualified advisor evaluates your exposure to various risks, including disability, long-term care, and premature death. They help you select the right insurance products to cover these gaps. This includes life insurance for legacy planning and disability insurance to protect your income. Without proper protection, a single unexpected event can derail your retirement plans.
Long-Term Care and Health Risks
Long-term care is a significant financial risk that many families underestimate. An advisor should discuss how long-term care insurance or other strategies can protect your assets from high care costs. They should also consider how healthcare costs impact your overall retirement budget. Understanding these risks allows you to make informed decisions about coverage and funding. according to Do Older Adults
Alignment with Your Family’s Goals and Values
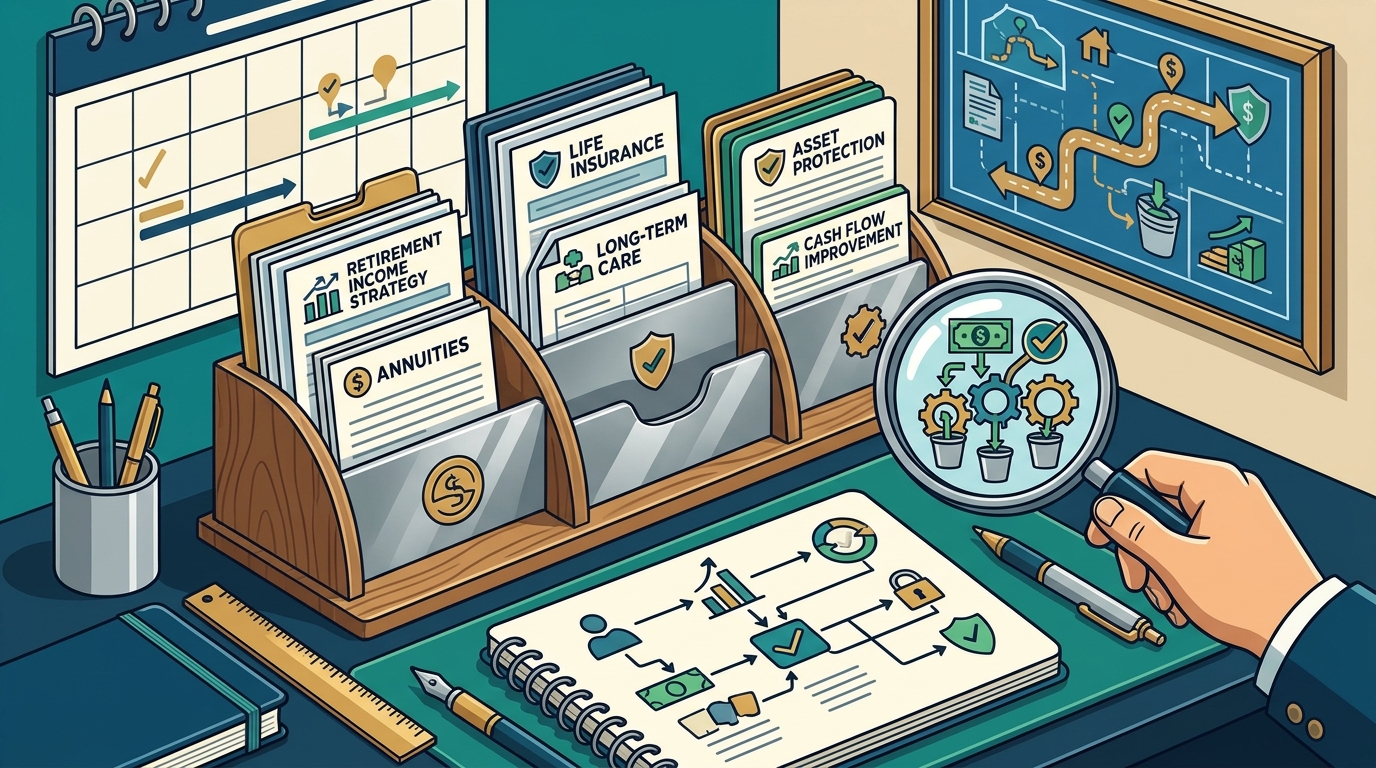
The best advisor listens to your specific goals and values before recommending products. They should ask about your desired lifestyle, legacy wishes, and risk tolerance. This alignment ensures that the strategy reflects your personal priorities. For example, if leaving a legacy for your children is important, the advisor will consider life insurance and estate planning implications. They should also discuss how your strategy supports your family’s long-term financial stability.
Legacy Planning and Wealth Transfer
Legacy planning is the process of transferring wealth to the next generation. An advisor can help you structure your assets to minimize tax impacts and ensure smooth transfer. They should discuss how life insurance can provide liquidity for estate taxes or leave a cash gift to heirs. This holistic view ensures that your retirement plan supports your broader family goals.
Transparency and Communication Style
Clear communication is essential for a successful advisor-client relationship. You should feel comfortable asking questions and understanding the rationale behind each recommendation. A transparent advisor explains fees, product features, and potential risks in plain language. They should provide regular updates and be available when you need them. This open communication builds trust and ensures you are always informed about your plan’s performance.
Fee Structure and Compensation
Understanding how an advisor is compensated is crucial. Some advisors are paid commissions, while others charge fees. You should ask about all potential costs associated with their services and recommended products. A transparent advisor will explain how their compensation model aligns with your best interests. This clarity helps you avoid conflicts of interest and ensures you are getting fair value for their expertise.
Key Takeaways
- Look for an advisor who specializes in retirement income and insurance protection, not just general wealth management.
- Ensure the advisor understands how annuities and insurance products can create sustainable income and protect assets.
- Verify that the advisor addresses key risks such as disability, long-term care, and premature death.
- Choose an advisor who aligns with your family’s specific goals, values, and legacy wishes.
- Prioritize transparency in communication, fee structures, and product recommendations.
- Ask about the advisor’s experience with clients in your specific situation, such as business owners or healthcare professionals.
Frequently Asked Questions
What is the difference between a financial planner and an insurance advisor?
A financial planner typically focuses on overall financial goals, including investments and budgeting. An insurance advisor specializes in risk management and protection products. A retirement and insurance advisor combines both, focusing on creating income and protecting assets during retirement.
How do I know if an advisor is qualified to help with retirement income?
Look for certifications or designations that focus on retirement income planning. Ask about their experience with annuities and insurance products. A qualified advisor should be able to explain how these products work and how they fit into your overall strategy.
Should I use the same advisor for investments and insurance?
How much does it cost to work with a retirement and insurance advisor?
Costs vary depending on the advisor’s fee structure. Some charge commissions on products, while others charge hourly or flat fees. Ask for a clear breakdown of all costs before working with an advisor. Transparency in fees is a key indicator of a trustworthy professional.
Can an advisor help with tax implications of retirement income?
While an insurance advisor may understand basic tax implications, they are not a tax professional. They can coordinate with a tax advisor to ensure your strategy is tax-efficient. This collaboration helps you minimize tax impacts on your retirement income and legacy.
Conclusion
Choosing the right retirement and insurance advisor is a critical decision for your family’s financial future. Look for a professional who specializes in income and protection, understands your goals, and communicates with transparency. At Generational Wealth Concepts, we help individuals, families, and business owners create strategies for retirement income, annuities, life insurance, long-term care, and legacy planning. We coordinate with specialized professionals when tax, estate-planning, or investment advice is needed. To plan your visit, to schedule a free strategy session.