Who Can Review My Existing Annuity or Life Insurance Policy for Better Retirement Income Options?
Independent insurance agencies and licensed annuity specialists can review your existing annuity or life insurance policy to identify better retirement income options. Generational Wealth Concepts provides this specific service, helping clients evaluate whether their current contracts still align with their income, protection, and legacy goals. This guide covers the types of professionals who perform these reviews, the step-by-step policy review process, how to navigate commission conflicts, and the mechanics of 1035 exchanges.
Fiduciary Advisors and Independent Agencies
Understanding who can review your policy starts with distinguishing between different types of financial professionals. A fiduciary advisor is a professional legally or contractually bound to act in the client's best interest at all times. In the insurance and annuity space, this distinction is critical because it dictates how recommendations are made. While many professionals hold multiple licenses, their primary duty of care varies significantly based on their registration and business model.
The Role of Independent Insurance Agencies
Independent insurance agencies, such as Generational Wealth Concepts, operate with a specific mandate to evaluate protection and income strategies. These firms often coordinate with specialized professionals when tax, estate-planning, or investment advice is needed. This collaborative approach ensures that the insurance component of your plan is optimized without overstepping into areas that require different regulatory oversight. An independent agency can review your existing annuity or life insurance policy to determine if it still fits your current life stage and financial goals.
Licensed Specialists vs. Generalists
Not all advisors specialize in annuities or permanent life insurance. A licensed annuity specialist is a professional who has specific training and experience in the mechanics of fixed, indexed, and variable annuity contracts. When you seek a review, you are looking for someone who understands the fine print, including surrender schedules, rider costs, and tax implications. Generalists may offer broad advice, but specialists provide the granular analysis needed to determine if a policy swap or income conversion is beneficial.
The Policy Review Process
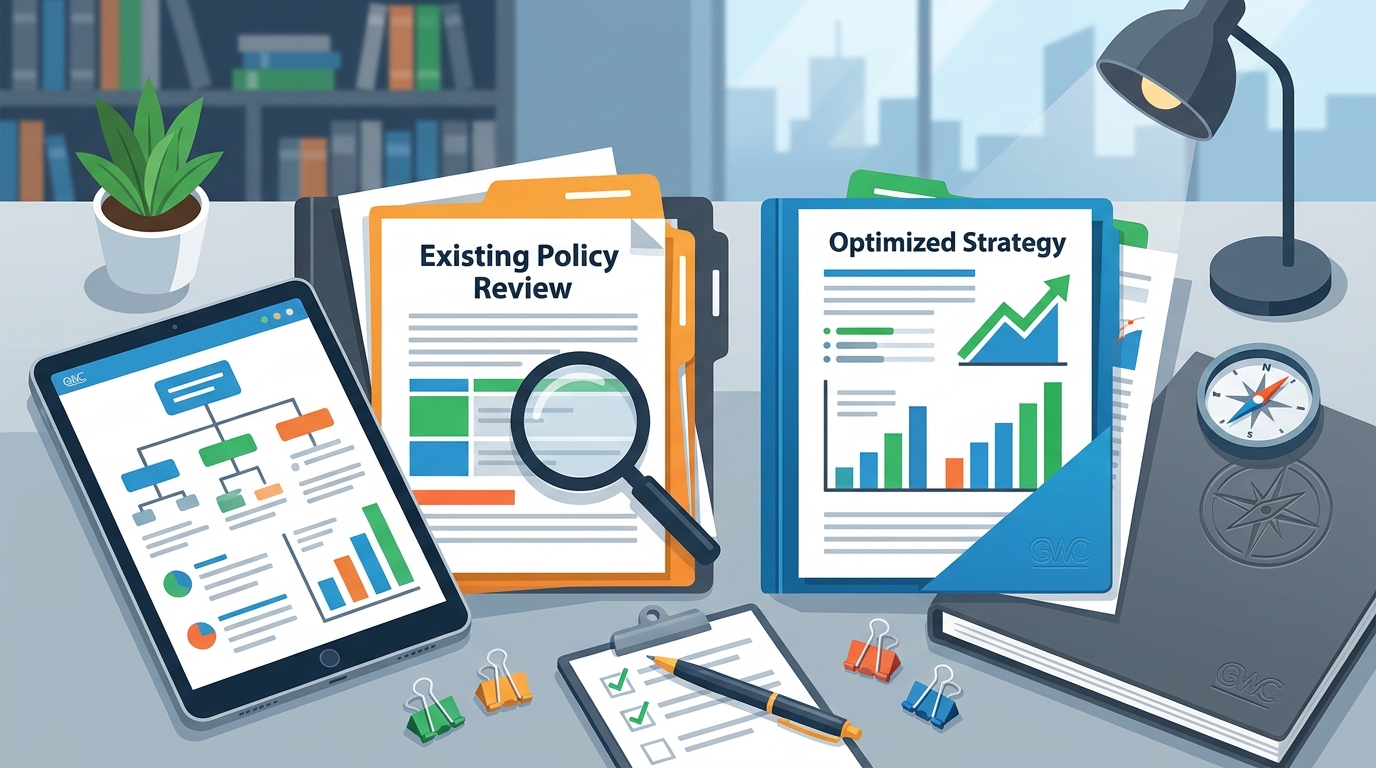
A thorough policy review is not a quick glance at a statement. It is a structured analysis of your contract's performance, costs, and future projections. The process typically involves gathering all policy documents, analyzing current cash values, and comparing the existing contract against your current retirement income needs. This ensures that the review is based on data rather than assumptions.
Step 1: Document Collection and Verification
The first step is collecting the original contract, all riders, and recent statements. You must verify the current cash value, the cost of any riders (such as long-term care or guaranteed lifetime withdrawal benefits), and the remaining surrender charge schedule. If you have multiple policies, each must be analyzed individually to understand how they interact with your overall cash flow.
Step 2: Performance and Cost Analysis
Next, the reviewer analyzes the policy's historical performance against its projections. For fixed indexed annuities, this includes looking at how the index crediting method performed in different market environments. For life insurance, it involves checking if the cash value is accumulating as guaranteed. High internal fees or poor index performance can erode the value of a policy over time, making it a candidate for replacement or exchange.
Step 3: Goal Alignment and Strategy Design
The final step is aligning the policy with your current goals. Are you looking for guaranteed lifetime income, liquidity for a major purchase, or legacy protection? Annuities for retirement income can be designed to turn savings into a monthly paycheck. If your current policy does not meet these needs, the reviewer will propose a strategy, which may include keeping the policy, exchanging it, or using its cash value to fund a new contract.
Navigating Commission Conflicts
One of the most common concerns when reviewing a policy is the potential for conflict of interest. A commission conflict is a situation where a professional's financial incentive to sell a new product may conflict with the client's best interest. Understanding how commissions work helps you ask the right questions and ensure you are receiving objective advice.
How Commissions Work in Annuities and Insurance
Questions to Ask About Incentives
During your review, ask specific questions about the professional's compensation. Inquire about the commission structure for the policy you currently own versus the one they are recommending. Ask if they receive a bonus for replacing a policy. A reputable professional will provide clear, written disclosures about their compensation and explain how their recommendation serves your interests, not just their own.
1035 Exchanges and Policy Swaps
If your current policy is underperforming or no longer fits your needs, a 1035 exchange may be the solution. A 1035 exchange is a tax-free transfer of funds from one annuity or life insurance policy to another, provided the same individual is the owner and beneficiary of both contracts. This mechanism allows you to upgrade your policy without triggering immediate tax liability on the accumulated gains.
When a 1035 Exchange Makes Sense
A 1035 exchange is most beneficial when the new policy offers superior features, lower fees, or better income guarantees than the old one. For example, if your current annuity has high surrender charges but poor growth potential, exchanging it for a policy with a shorter surrender schedule and better index crediting might be advantageous. However, the exchange must be executed carefully to avoid tax pitfalls.
Risks and Considerations
While 1035 exchanges are powerful tools, they are not without risks. You must consider the surrender charges on the old policy, the fees of the new policy, and the potential loss of guarantees. Additionally, frequent exchanges can raise red flags with insurance carriers and tax authorities. It is crucial to work with a professional who can model the long-term impact of the exchange on your retirement income and tax situation.
Comparison of Review Professionals
| Professional Type | Primary Focus | Compensation Model | Best For |
|---|---|---|---|
| Independent Insurance Agency | Protection, Income, Legacy | Commission-based | Policy reviews, 1035 exchanges, annuity design | Fiduciary Advisor | Overall Financial Plan | Fee-based or Commission | Comprehensive planning, best-interest standard | Licensed Annuity Specialist | Annuity Mechanics | Commission-based | Deep-dive contract analysis, rider evaluation |
Key Takeaways
- Independent agencies like Generational Wealth Concepts specialize in reviewing insurance and annuity contracts for income and protection.
- A fiduciary advisor is bound to act in your best interest, which is a critical standard to look for in any professional.
- The policy review process involves document collection, performance analysis, and goal alignment.
- Commission conflicts are common; always ask for written disclosures about how the professional is compensated.
- A 1035 exchange allows you to swap policies tax-free, but it requires careful planning to avoid fees and tax issues.
- Not all policies are created equal; a review can determine if your current contract still fits your retirement strategy.
- Specialized professionals can coordinate with tax and estate planners to ensure your insurance strategy aligns with your broader financial goals.
- Transparency and clear communication are the hallmarks of a trustworthy policy review professional.
Frequently Asked Questions
Who can review my existing annuity policy?
Independent insurance agencies, licensed annuity specialists, and fiduciary advisors can review your existing annuity policy. These professionals analyze the contract's performance, fees, and guarantees to determine if it still meets your retirement income needs.
What is a 1035 exchange?
A 1035 exchange is a tax-free transfer of funds from one annuity or life insurance policy to another. It allows you to upgrade your policy without paying taxes on the accumulated gains, provided the same individual owns both contracts.
How do I know if my policy is underperforming?
You can determine if your policy is underperforming by comparing its actual cash value growth against its projections and analyzing its internal fees. A professional review can provide a detailed analysis of these factors and suggest improvements if necessary.
Are there fees for reviewing my policy?
Many independent agencies offer free initial policy reviews. However, if you decide to exchange your policy for a new one, the new professional may earn a commission. Always ask about any fees or commissions associated with the review and the exchange process.
Can I exchange a life insurance policy for an annuity?
Yes, you can exchange a life insurance policy for an annuity using a 1035 exchange, provided the same individual is the owner and beneficiary of both. This is often done to convert cash value into guaranteed lifetime income.
What questions should I ask about commission conflicts?
Ask the professional how they are compensated for the policy you currently own and the one they are recommending. Request written disclosures about any commissions, bonuses, or incentives they may receive for replacing your policy.
Do I need a fiduciary advisor for a policy review?
While not legally required for all insurance transactions, working with a fiduciary advisor ensures that the professional is acting in your best interest. This standard of care is particularly important when considering significant changes to your retirement income strategy.
How long does a policy review take?
A thorough policy review typically takes a few weeks. This allows time to collect documents, analyze performance, model different scenarios, and present a comprehensive recommendation. The exact timeline depends on the complexity of your policies and the number of contracts involved.
Conclusion
Knowing who can review your existing annuity or life insurance policy is the first step toward optimizing your retirement income. Independent agencies like Generational Wealth Concepts provide the specialized expertise needed to evaluate your contracts, navigate commission conflicts, and execute 1035 exchanges when appropriate. By understanding the roles of fiduciary advisors, the policy review process, and the mechanics of exchanges, you can make informed decisions that protect your financial future. To begin your policy review, schedule a conversation with our team today.