Legal Strategies to Protect Business Assets in Privatized Banking
Asset protection in privatized banking relies on legal structuring that separates personal wealth from business liabilities. By using properly designed permanent life insurance policies, entrepreneurs can create a liquid asset that is generally shielded from business creditors. This approach allows you to build retirement income while maintaining a legal firewall between your personal financial safety net and your company's operational risks.
The Legal Framework for Asset Protection
Privatized banking is a strategy that uses the cash value of a permanent life insurance policy as a source of liquidity. Unlike business accounts, personal life insurance policies often benefit from statutory protections under state law. These laws typically prevent creditors from seizing the cash value of a life insurance policy to satisfy personal debts. This legal distinction is the foundation of the asset protection strategy.
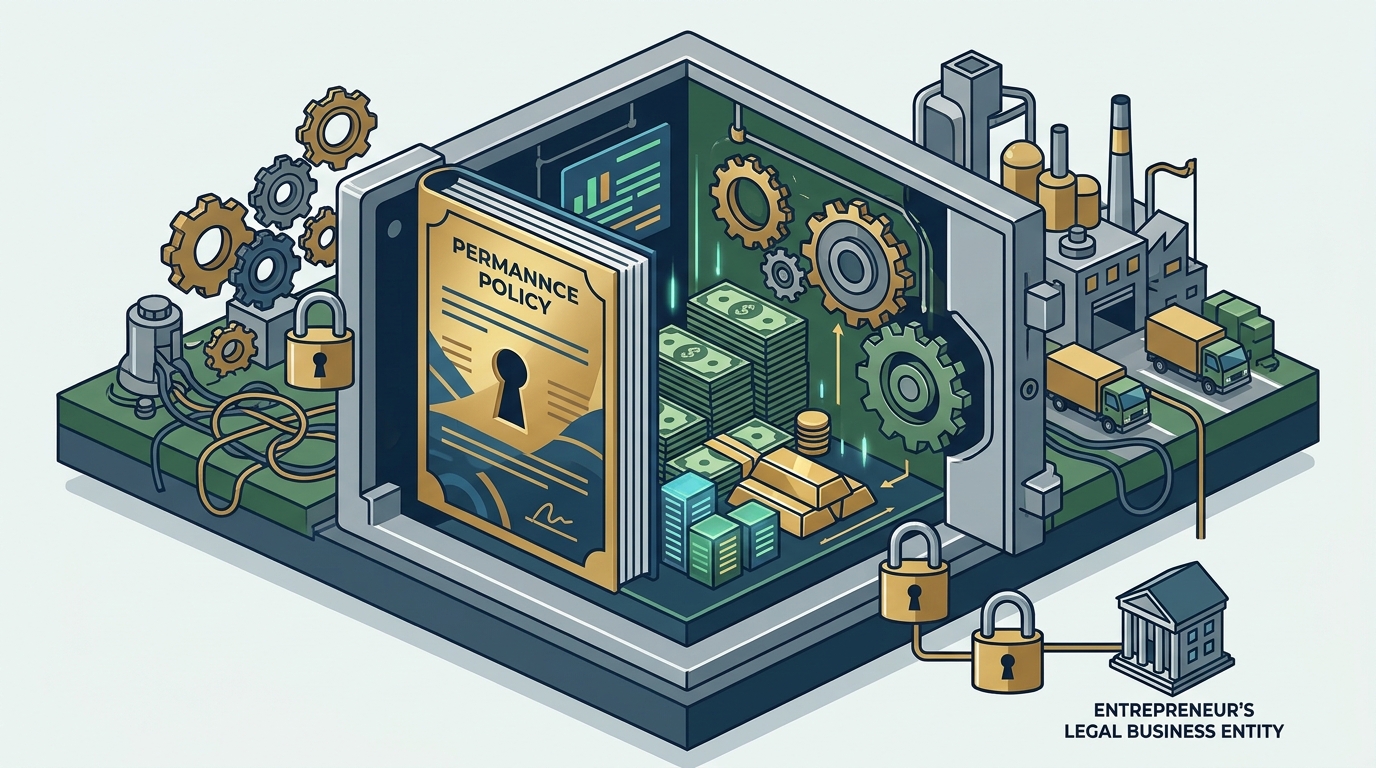
The primary legal mechanism is the exemption of life insurance proceeds and cash value from creditor claims. In many jurisdictions, the cash value of a life insurance policy is considered a protected asset. This means that if a business faces a lawsuit or bankruptcy, the personal policy held by the owner may remain untouched. The key is ensuring the policy is owned by the individual, not the business entity. This separation creates a clear legal boundary that protects the retirement income stream.
Entity Structuring and Ownership
Proper entity structuring is critical to maintaining the legal firewall between business assets and personal wealth. When you form an LLC or corporation, you create a separate legal entity. This entity is responsible for its own debts and liabilities. However, if you commingle personal and business funds, you risk piercing the corporate veil. This legal doctrine allows creditors to access personal assets to satisfy business debts. To avoid this, you must maintain strict separation between personal and business finances.
Ownership of the privatized banking policy should align with your overall legal structure. Typically, the individual owner of the business holds the life insurance policy. This ensures the policy remains a personal asset, protected by state insurance laws. If the business entity owns the policy, it may be considered a business asset and subject to business creditors. Therefore, the policy should be owned by the individual, with the business potentially being the beneficiary or having a loan agreement in place. This structure preserves the legal protection of the cash value while allowing the business to benefit from the liquidity if needed.
Policy Design and State Law
Policy design plays a significant role in the effectiveness of asset protection. The type of life insurance policy used in privatized banking must be carefully selected to maximize legal protections. Whole life insurance policies are commonly used because they offer guaranteed cash value growth and level premiums. The cash value accumulates over time, creating a substantial asset that can be accessed through policy loans. These loans are not considered taxable income, which adds another layer of financial flexibility.
State laws vary regarding the extent of protection for life insurance cash value. Some states offer stronger protections than others, and the specific language of the law can impact how the policy is treated in legal proceedings. It is essential to understand the laws in your state of residence and where the business is located. For example, some states may limit the amount of cash value that is protected, while others may offer full protection. Consulting with a legal professional who specializes in insurance and asset protection is crucial to ensure the policy design aligns with your state's laws and your specific circumstances.
Business Continuity and Key Person Coverage
Business continuity is another important aspect of asset protection in privatized banking. If a key employee or business owner becomes disabled or passes away, the business may face significant financial challenges. Key person life insurance is a policy that the business owns to protect against the loss of a critical individual. This policy provides the business with funds to cover expenses, hire a replacement, or stabilize operations during a transition period.
While key person insurance is owned by the business, it serves a different purpose than the personal privatized banking policy. The personal policy protects the owner's retirement income and personal wealth, while the key person policy protects the business's operational stability. Having both types of coverage ensures that both personal and business assets are protected. This dual approach provides a comprehensive safety net that addresses the unique risks faced by entrepreneurs and business owners. It is important to coordinate these policies with your legal and financial strategies to ensure they work together effectively.
Coordinating with Legal Professionals
Coordinating with legal professionals is essential to implement and maintain an effective asset protection strategy. Generational Wealth Concepts works with independent licensed professionals who provide legal, tax, and estate-planning services. This collaboration ensures that the privatized banking strategy is aligned with your overall legal and financial goals. A legal professional can review the policy structure, entity formation, and state laws to ensure that the asset protection strategy is sound and compliant.
Regular reviews of your legal and financial situation are also important. As your business grows and your personal circumstances change, your asset protection strategy may need to be adjusted. Working with a team of professionals who understand the intersection of insurance, law, and finance can help you stay ahead of potential risks. This proactive approach ensures that your retirement income and personal wealth remain protected as you navigate the complexities of business ownership.
Key Takeaways
- Privatized banking uses permanent life insurance cash value as a liquid asset for retirement income.
- State laws often protect personal life insurance cash value from business creditors.
- Proper entity structuring and separation of personal and business funds are critical to maintaining the legal firewall.
- The policy should be owned by the individual, not the business entity, to preserve legal protections.
- Key person insurance protects the business's operational stability, complementing personal asset protection.
- Coordinating with legal professionals ensures the strategy is compliant and aligned with your goals.
- Regular reviews of your legal and financial situation help maintain an effective asset protection strategy.
Frequently Asked Questions
Does privatized banking protect my personal assets from business lawsuits?
Yes, if the life insurance policy is owned by the individual and not the business entity, the cash value is often protected by state law from business creditors. This legal distinction helps shield your personal wealth from business liabilities.
Can a business entity own a privatized banking policy?
While a business can own a life insurance policy, doing so may expose the cash value to business creditors. To maintain asset protection, the policy should typically be owned by the individual business owner.
What is the role of entity structuring in asset protection?
Entity structuring creates a legal separation between personal and business assets. Proper structuring helps prevent the piercing of the corporate veil, which could otherwise expose personal assets to business debts.
How does state law affect the protection of life insurance cash value?
State laws vary in how they protect life insurance cash value from creditors. Some states offer full protection, while others may have limitations. Understanding your state's laws is essential for designing an effective asset protection strategy.
What is key person insurance and how does it relate to asset protection?
Key person insurance is a policy owned by the business to protect against the loss of a critical individual. It provides funds to stabilize the business during a transition, complementing personal asset protection strategies.
Do I need a legal professional to implement a privatized banking strategy?
Yes, working with a legal professional is recommended to ensure that the policy structure and entity formation are compliant with state laws and aligned with your asset protection goals.
How often should I review my asset protection strategy?
It is advisable to review your asset protection strategy regularly, especially as your business grows and your personal circumstances change. This ensures that your strategy remains effective and compliant.
Conclusion
Protecting your business assets while building retirement income through privatized banking requires a thoughtful approach to legal structuring. By understanding the legal framework, proper entity structuring, and state laws, you can create a robust asset protection strategy. Generational Wealth Concepts helps individuals, families, and business owners design strategies that balance growth, protection, and legacy. To discuss how privatized banking can fit into your overall financial plan, for a personalized consultation.