A fiduciary advisor acts in your best interest when reviewing retirement insurance policies. They evaluate whether your current contracts align with your income goals and risk tolerance. This review ensures you are not overpaying for features you do not need. Generational Wealth Concepts helps clients understand these obligations clearly.
The Legal Standard of Care
Fiduciary duty is a legal and ethical obligation to act solely in the client's best interest. This standard is stricter than a mere suitability standard. A fiduciary must disclose all conflicts of interest. They must also prioritize your financial well-being over their own compensation.
When reviewing an annuity or life insurance policy, this duty changes the conversation. The advisor cannot simply sell you a new product. They must prove that a change is necessary. If your current policy works, the fiduciary will say so. This honesty builds trust and prevents unnecessary fees.
Generational Wealth Concepts operates with a focus on protection and income stability. We explain how fiduciary principles apply to insurance contracts. We help you see the difference between a sales pitch and a true review.
Contract Analysis and Fee Transparency
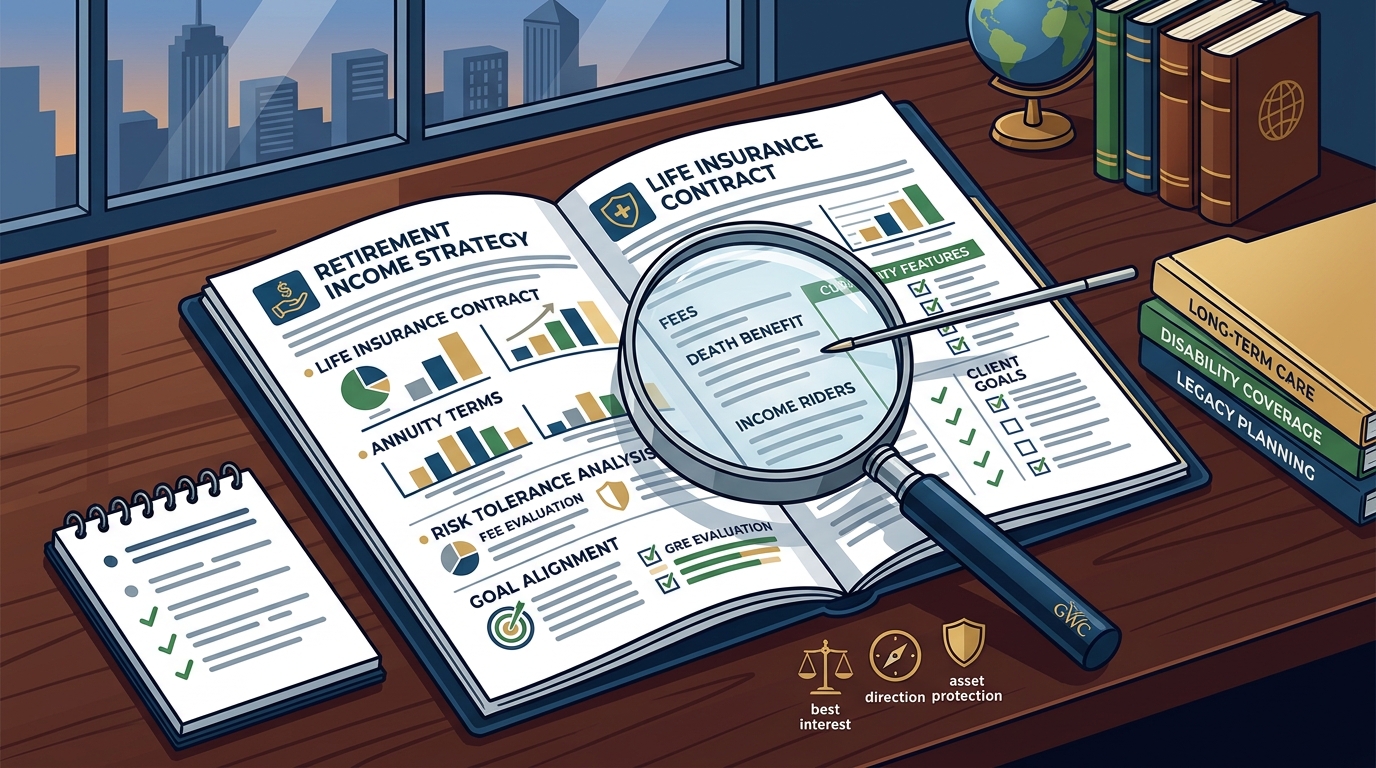
The first step in a fiduciary review is a deep dive into your contract. The advisor reads the fine print. They look for surrender charges, rider costs, and fee structures. They calculate the total cost of ownership over time.
For example, a fixed annuity might have a 7% surrender charge in year one. A fiduciary will calculate if you can access your funds if an emergency occurs. They will also check for hidden administrative fees. These fees can erode your principal over decades. Transparency is the core of this process.
We encourage clients to ask for a full fee breakdown. You should know exactly what you pay for each feature. If a rider is not being used, a fiduciary will suggest removing it. This can lower your annual cost significantly.
Income Strategy and Risk Assessment
Retirement income planning is the creation of a sustainable cash flow strategy for your post-work years. A fiduciary advisor evaluates if your insurance policies support this goal. They look at the timing and amount of payouts. They also assess the risk of outliving your money.
Consider a client with a variable annuity. The advisor will check if the income rider is guaranteed. They will also look at the market performance of the underlying funds. If the market drops, does your income drop too? A fiduciary will model these scenarios. They will show you the downside risk clearly.
At Generational Wealth Concepts, we focus on stability. We help you understand how your policies fit into your broader income plan. We ensure that your insurance assets work for you, not against you.
Conflict of Interest Disclosure
For instance, an advisor might earn a higher commission on a new policy. A fiduciary must tell you this. They must also explain why a new policy is better than keeping the old one. If they cannot justify the switch, they should not recommend it. This disclosure protects you from biased advice.
We believe in full transparency. We explain our compensation model to every client. You should always know how your advisor makes money. This knowledge empowers you to make informed decisions.
Long-Term Legacy and Protection
Legacy planning is the process of transferring wealth to future generations or charitable causes. A fiduciary advisor reviews your policies for their legacy impact. They check if your beneficiaries are up to date. They also assess if the death benefit is sufficient.
Life insurance plays a key role in this. A fiduciary will look at the type of policy. Is it term or permanent? Does it have cash value? They will evaluate if the policy is still relevant to your estate. If you no longer need the death benefit, they may suggest a different strategy.
Generational Wealth Concepts helps families protect their assets. We ensure that your insurance policies support your long-term goals. We help you leave a legacy that lasts.
Key Takeaways
- A fiduciary advisor must act in your best interest at all times.
- They must disclose all conflicts of interest and compensation structures.
- Contract analysis is a core part of the review process.
- Income strategy and risk assessment are critical for retirement planning.
- Legacy planning ensures your policies support your long-term goals.
- Transparency and honesty are the hallmarks of a true fiduciary.
Frequently Asked Questions
What is the difference between a fiduciary and a suitability standard?
A fiduciary must act in your best interest. A suitability standard only requires that a product is suitable for you. The fiduciary standard is stricter and offers more protection.
Can a fiduciary advisor sell me a new insurance policy?
Yes, but only if it is in your best interest. They must prove that the new policy is better than your current one. They must also disclose any conflicts of interest.
How do I know if my advisor is a fiduciary?
Ask them directly. A true fiduciary will confirm their status in writing. They will also explain their legal obligations to you.
What should I ask during a policy review?
Ask about fees, surrender charges, and income guarantees. Ask how the policy fits into your overall retirement plan. Ask about any conflicts of interest.
Does Generational Wealth Concepts provide fiduciary advice?
Generational Wealth Concepts is an independent insurance agency. We focus on protection and income stability. We coordinate with licensed professionals when specific fiduciary advice is needed.
Conclusion
A fiduciary review of your retirement insurance policies is a powerful tool. It ensures that your assets work for you. It protects you from unnecessary fees and conflicts. Generational Wealth Concepts is here to help you understand this process. We help you build a retirement strategy designed for income, protection, and legacy. To plan your visit, contact our team.