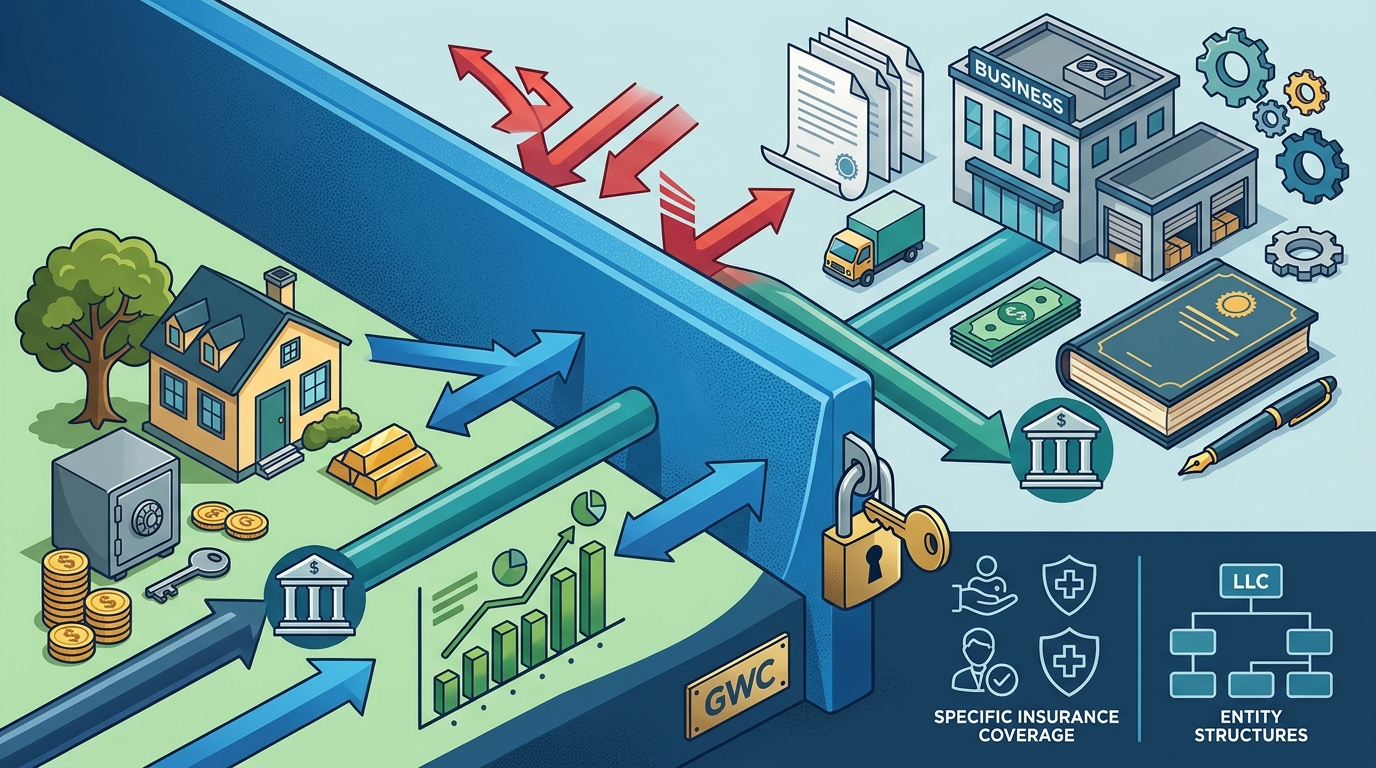
Small business owners can prevent personal bankruptcy from business debt by establishing clear legal boundaries between personal and business finances. This involves using appropriate business entity structures, maintaining separate accounts, and securing specific insurance coverage. Generational Wealth Concepts helps business owners in Frisco, TX, and beyond build these protective layers to ensure that business liabilities do not erode personal wealth or retirement security.
Legal Structures and Liability Shields
The most fundamental step in protecting personal assets is choosing the right legal entity for your business. A sole proprietorship offers no legal separation between the owner and the business, meaning personal assets are directly exposed to business debts. In contrast, a Limited Liability Company (LLC) or a corporation creates a legal entity that is distinct from its owners. This structure is designed to limit the personal liability of the owners for business obligations. However, this protection is not absolute. Courts can "pierce the corporate veil" if the business and personal finances are commingled or if the entity is not maintained properly. Therefore, the legal structure is the first line of defense, but it requires consistent operational discipline to remain effective.
Maintaining Strict Financial Separation
Even with a strong legal structure, personal assets remain at risk if business and personal finances are mixed. This practice, known as commingling, undermines the liability shield provided by an LLC or corporation. To maintain this separation, business owners must use dedicated business bank accounts and credit cards for all business transactions. Personal expenses should rarely be paid directly from business accounts, and business expenses should not be paid from personal accounts. Additionally, business owners should avoid using personal assets as collateral for business loans unless absolutely necessary. If a personal guarantee is required for a business loan, the lender can pursue personal assets if the business defaults. Understanding the terms of these guarantees is critical for risk management.
Insurance as a Financial Firewall
Insurance serves as a critical financial firewall against unexpected business liabilities. While legal structures protect against general business debts, insurance protects against specific risks that could lead to significant financial loss. For example, general liability insurance covers third-party bodily injury or property damage claims. If a customer is injured on your business premises, this coverage can prevent a lawsuit from draining personal assets. Similarly, professional liability insurance, also known as errors and omissions insurance, protects against claims of negligence or failure to perform services. These policies are essential for service-based businesses. By transferring specific risks to an insurance carrier, business owners can prevent a single claim from triggering a cascade of financial distress that could lead to personal bankruptcy.
Debt Protection and Mortgage Insurance
Many small business owners rely on their personal income to service business debts, such as equipment loans or lines of credit. If the owner becomes unable to work due to illness or injury, the business may struggle to generate cash flow, leading to default on these debts. This is where debt protection insurance becomes relevant. This type of coverage is designed to pay off or make payments on specific debts if the policyholder becomes disabled or dies. For business owners with significant personal guarantees on business loans, this coverage can prevent the debt from falling entirely on the family or personal estate. Generational Wealth Concepts offers guidance on mortgage protection insurance and other debt protection strategies that align with your overall wealth protection plan. This ensures that a personal health event does not translate into a business failure and subsequent personal bankruptcy.
Safeguarding Retirement and Long-Term Wealth
Business owners often invest heavily in their companies, sometimes at the expense of their retirement savings. If the business fails, the owner may find themselves without a business and without a retirement fund. To prevent this, it is crucial to maintain a diversified retirement strategy that is separate from business assets. This includes contributing to individual retirement accounts (IRAs) or other retirement vehicles that are protected under federal law to varying degrees. Additionally, long-term care planning is a vital component of wealth protection. If an owner requires long-term care, the costs can be substantial and may deplete personal assets. Generational Wealth Concepts provides long-term care planning services to help owners secure their future care needs without jeopardizing their legacy. By addressing both retirement income and care costs, owners can build a more resilient financial foundation that withstands business volatility.
Key Takeaways
- Choose a legal entity like an LLC or corporation to create a legal separation between personal and business assets.
- Maintain strict financial separation by using dedicated business accounts and avoiding commingling of funds.
- Secure appropriate insurance coverage, such as general liability and professional liability, to protect against specific claims.
- Consider debt protection insurance to ensure business loans are serviced if you become disabled or pass away.
- Diversify retirement savings to ensure personal financial security independent of business performance.
- Plan for long-term care to prevent healthcare costs from depleting personal assets.
- Regularly review your legal and insurance structures with professional guidance to ensure they remain effective.
Frequently Asked Questions
Does an LLC protect my personal assets from all business debts?
An LLC provides a legal shield that generally protects personal assets from business debts. However, this protection can be lost if you commingle personal and business funds or if you personally guarantee a business loan. It is important to maintain strict financial separation and understand the terms of any personal guarantees.
What happens if I personally guarantee a business loan?
If you personally guarantee a business loan, the lender can pursue your personal assets if the business defaults on the loan. This means your home, savings, and other personal property could be at risk. Debt protection insurance can help mitigate this risk by ensuring loan payments are made if you become unable to work.
How does insurance help prevent personal bankruptcy?
Insurance helps prevent personal bankruptcy by covering specific risks that could lead to large financial losses. For example, liability insurance covers claims for injury or damage, preventing a lawsuit from draining personal assets. By transferring these risks to an insurance carrier, you protect your personal wealth from business-related liabilities.
What is the difference between business debt and personal debt?
Business debt is incurred by the business entity for business purposes, while personal debt is incurred by the individual for personal use. If you have a properly structured business entity and maintain financial separation, business debt should not affect your personal assets. However, if you personally guarantee business debt, it becomes a personal obligation.
Should I use my home as collateral for a business loan?
Using your home as collateral for a business loan puts your personal residence at risk if the business fails to repay the loan. This is a significant risk that should be carefully considered. If you must use your home as collateral, consider obtaining mortgage protection insurance to ensure the loan is paid off if you become disabled or pass away.
How can I protect my retirement savings from business failure?
To protect your retirement savings, ensure they are held in separate accounts that are not commingled with business funds. Diversify your retirement investments and consider using retirement vehicles that offer legal protection, such as IRAs. Additionally, maintain a separate emergency fund for personal expenses that is not tied to business cash flow.
Building a Resilient Financial Foundation
Preventing personal bankruptcy from business debt requires a proactive approach to legal, financial, and insurance planning. By establishing the right legal structure, maintaining strict financial separation, and securing appropriate insurance coverage, small business owners can protect their personal assets and ensure long-term financial stability. Generational Wealth Concepts is dedicated to helping business owners in Frisco, TX, and across the region build these protective layers. We work with you to assess your specific risks and design a comprehensive wealth protection plan that aligns with your business goals and personal financial security. To discuss how we can help you protect your personal assets from business debt, for a consultation.