Who Can Help Families Build a Retirement Income and Insurance Strategy?
Generational Wealth Concepts is an independent insurance agency and retirement income strategy firm that helps families coordinate protection, income, and legacy goals. We focus on insurance and annuity strategies rather than investment management. This guide explains how to identify the right professional for your specific needs and how insurance products integrate into a broader retirement plan.
Understanding the Role of an Insurance Strategy Firm
Many families assume that retirement planning is solely about growing assets. In reality, the core challenge is often about creating reliable income and protecting that income from risk. An insurance strategy firm focuses on the protection and income components of your financial life. This includes managing longevity risk, market volatility, and unexpected healthcare costs.
At Generational Wealth Concepts, we help individuals, families, and business owners create strategies for retirement income, annuities, life insurance, long-term care, and legacy planning. We make personal finance simple and understandable by customizing it to your specific needs. Our mission is to help clients understand and coordinate strategies for retirement income, protection, liquidity, and legacy. We believe retirement planning should address more than accumulation alone. Income needs, market risk, taxes, healthcare, and the desire to leave a legacy all affect which strategies are appropriate.
When a client's plan involves tax, legal, estate-planning, or investment advice outside our scope, we coordinate with qualified professionals. This ensures that all areas of your financial life are addressed as part of a broader, cohesive strategy. We help individuals, banks, entrepreneurs, and business owners build protection, safety, and stability into their financial cash flow.
Financial Planner Qualifications and Scope
Choosing the right professional requires understanding the specific qualifications and scope of practice for different types of advisors. The term financial planner is often used broadly, but the regulatory scope varies significantly depending on the license held. It is critical to distinguish between those who provide insurance strategies and those who manage investment portfolios.
Licenses and Certifications
Insurance professionals typically hold state-issued licenses that allow them to sell and service insurance products. These licenses cover specific lines of authority, such as life, health, and annuities. At Generational Wealth Concepts, our team is licensed and independent, allowing us to access a broad range of highly rated carriers. We are not bound to a single insurance company, which allows us to design strategies around your specific protection and income goals rather than pushing a single product.
It is important to verify the specific licenses held by any professional you consult. A professional who focuses on insurance and retirement income strategies will have deep expertise in annuities, life insurance, and long-term care. They will understand how these products interact with your existing retirement accounts. However, they may not hold licenses to provide individualized investment advice or manage securities.
Scope of Practice
The scope of practice defines what a professional is legally allowed to do. An insurance strategy firm focuses on risk management and income generation through insurance contracts. We help clients evaluate whether permanent life insurance can be one component of a broader financial strategy. This may offer death-benefit protection and cash-value features that provide additional flexibility. We help clients evaluate these strategies alongside annuities and other retirement resources based on their individual circumstances.
Generational Wealth Concepts is an independent insurance agency and retirement income strategy firm. We do not directly provide securities, investment advisory, legal, tax preparation, or estate-planning legal services. When appropriate, we may coordinate with independent licensed professionals who provide those services. This clear delineation of scope ensures that you receive specialized advice in the areas where we have the most expertise.
Insurance Product Integration in Retirement
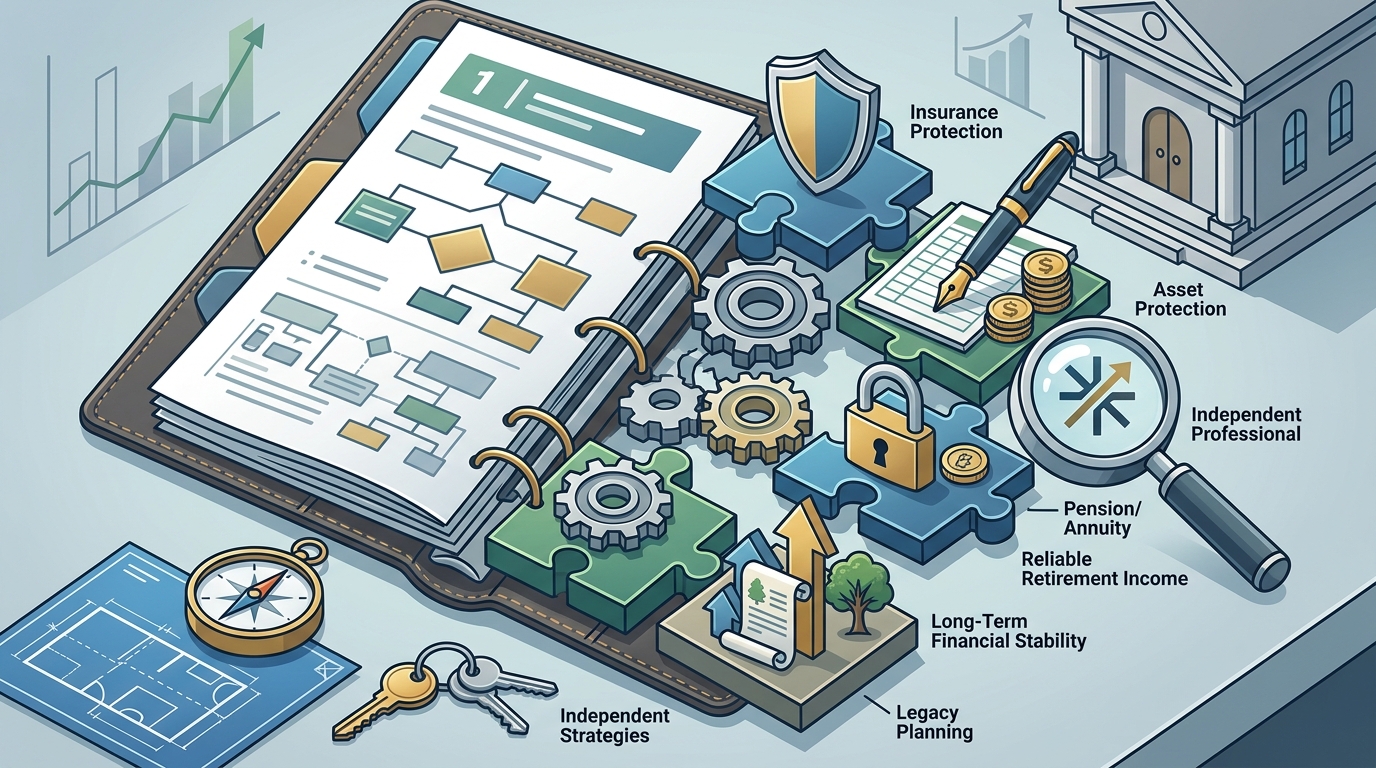
Insurance products are not just for protection; they are powerful tools for creating retirement income. Integrating these products into your retirement plan can provide stability, tax advantages, and liquidity. The key is to understand how each product type functions and how it fits into your overall financial picture.
Annuities for Guaranteed Income
An annuity is a contract with an insurance company that provides a stream of payments over time. For retirement, annuities can provide principal protection, growth potential, and guaranteed lifetime income. We help you determine whether an annuity fits your retirement strategy and whether the annuity you already own is still a good fit. Fixed annuities offer steady, predictable interest rates with principal protection. Fixed indexed annuities offer growth potential linked to a market index while protecting your account value from negative index performance.
Income annuities allow you to turn a portion of your savings into a monthly retirement paycheck for life. This can be a crucial component of a retirement plan, especially if you are worried about outliving your savings. Hybrid annuities with long-term care riders provide income and long-term care coverage in one plan. This integration can simplify your planning and reduce the risk of depleting your assets due to extended care needs.
Life Insurance for Legacy and Liquidity
Life insurance is often viewed solely as a death benefit, but it can play a significant role in retirement planning. Whole life insurance can provide lifetime death-benefit protection, level premiums, and guaranteed cash-value growth when policy requirements are met. This cash value can be accessed through withdrawals or policy loans, providing a source of liquidity for opportunities or major purchases. This concept is often referred to as privatized banking.
Privatized banking uses a properly structured permanent life insurance policy to combine life insurance protection with access to policy cash value. For the right person, it can create another source of liquidity and financial flexibility. We help clients evaluate whether this strategy makes sense for their goals. It is important to note that policy loans accrue interest and can reduce cash value and death benefits if not repaid. Therefore, this strategy requires careful planning and monitoring.
Long-Term Care and Disability Protection
Retirement planning must also account for the risks of disability and long-term care. Disability insurance ensures your paycheck continues if you are unable to work due to illness or injury. This is particularly important for self-employed professionals and business owners. Long-term care planning is about preparing for the possibility of needing help with everyday care for an extended period. A long-term care event can affect more than healthcare; it can change how retirement assets are spent and what may ultimately be left for family.
We help clients compare traditional long-term care insurance, life insurance with long-term care or chronic-illness benefits, and other available strategies. The objective is to understand the tradeoffs before a care need arises. Long-term care planning is generally easier when more options are still available. Age and health can affect eligibility, benefits, and cost, so reviewing the available approaches before a care need develops can be useful.
Comparing Professional Roles
Understanding the differences between various financial professionals can help you build the right team for your retirement strategy. The table below summarizes the primary focus and scope of practice for different types of advisors.
| Professional Type | Primary Focus | Scope of Practice | Key Products/Services |
|---|---|---|---|
| Insurance Strategy Firm | Risk management, retirement income, legacy | Insurance products, annuities, long-term care | Annuities, life insurance, disability insurance |
| Investment Advisor | Portfolio growth, asset management | Securities, mutual funds, ETFs | Stocks, bonds, investment portfolios |
| Tax Professional | Tax planning, compliance | Tax preparation, tax strategy | Tax returns, tax optimization |
| Estate Planning Attorney | Legal structure, asset transfer | Wills, trusts, estate documents | Wills, trusts, powers of attorney |
At Generational Wealth Concepts, we focus on the insurance and retirement income strategy side of the equation. We coordinate with tax, legal, estate-planning, and investment professionals when specialized advice is needed. This collaborative approach ensures that all aspects of your financial life are addressed by qualified experts.
Key Takeaways
- Generational Wealth Concepts is an independent insurance agency and retirement income strategy firm.
- We focus on insurance and annuity strategies, not investment management or securities.
- Our team is licensed and independent, allowing access to a broad range of highly rated carriers.
- Annuities can provide principal protection, growth potential, and guaranteed lifetime income.
- Whole life insurance can offer cash-value features that provide additional flexibility and liquidity.
- Long-term care and disability insurance are critical components of a comprehensive retirement plan.
- We coordinate with qualified professionals for tax, legal, estate-planning, or investment advice outside our scope.
- Our goal is to help clients make informed decisions based on their goals rather than relying on a one-size-fits-all approach.
Frequently Asked Questions
What is the difference between an insurance strategy firm and an investment advisor?
An insurance strategy firm focuses on risk management, retirement income, and legacy planning using insurance products. An investment advisor focuses on portfolio growth and asset management using securities. At Generational Wealth Concepts, we focus on the former and coordinate with investment advisors when needed.
Can annuities be used for retirement income?
Yes, annuities can provide guaranteed lifetime income. Income annuities allow you to turn a portion of your savings into a monthly retirement paycheck for life. This can help protect against the risk of outliving your savings.
What is privatized banking?
Privatized banking uses a properly structured permanent life insurance policy to combine life insurance protection with access to policy cash value. For the right person, it can create another source of liquidity and financial flexibility.
Do you provide tax or legal advice?
No, Generational Wealth Concepts is an independent insurance agency and retirement income strategy firm. We do not directly provide securities, investment advisory, legal, tax preparation, or estate-planning legal services. When appropriate, we may coordinate with independent licensed professionals who provide those services.
How do I know if I have a good annuity?
An annuity is not good or bad simply because of its product type. What matters is whether its guarantees, fees, surrender period, income features, growth potential, and access to money still fit what you need it to accomplish. We can review an existing annuity and help you understand what you own before you decide whether any change makes sense.
Who needs long-term care insurance?
Anyone who wants to protect their retirement assets from the high cost of long-term care should consider long-term care insurance. A long-term care event can affect more than healthcare; it can change how retirement assets are spent and what may ultimately be left for family.
Conclusion
Building a retirement income and insurance strategy requires the right professional guidance. Generational Wealth Concepts helps families build retirement confidence, protection, and legacy. We make personal finance simple and understandable by customizing it to your needs. Whether you are looking to protect your income, create lifetime retirement paychecks, or build a stronger legacy, we would love to help you design a plan that sets up your future with confidence. To plan your visit, schedule a retirement strategy review with our team.