
Common Mistakes When Reviewing Your Annuity or Life Insurance Policy
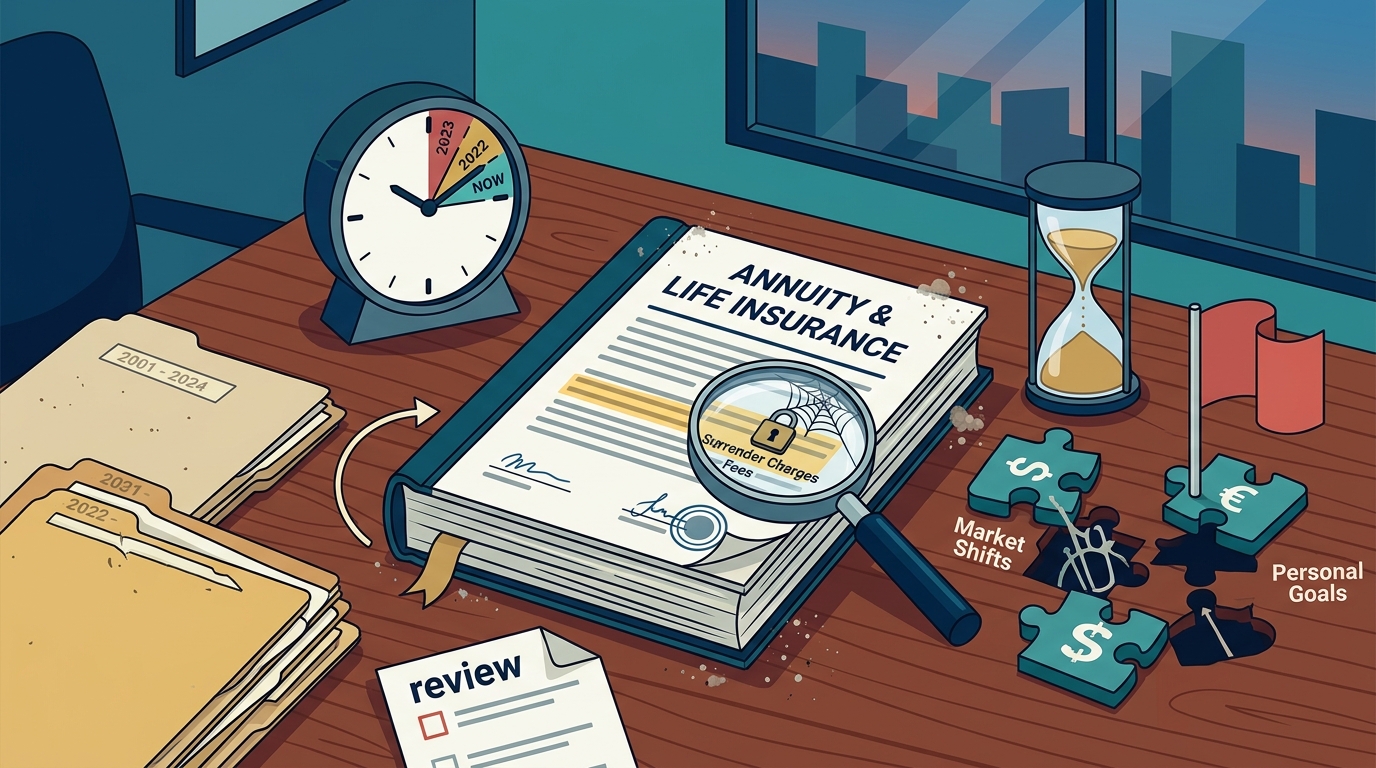
Many individuals hold insurance policies that no longer serve their current financial reality. According to recent industry data, a significant percentage of annuity holders are unaware of the specific surrender charges or fee structures embedded in their contracts. This lack of visibility often leads to costly decisions when market conditions shift or personal goals evolve. At Generational Wealth Concepts, we see clients who have let their policies sit on autopilot for years. The goal of this review is to help you identify critical errors before they impact your retirement income, protection, or legacy planning. (Contact Generational Wealth Concepts)
Ignoring Surrender Charges and Liquidity Traps
One of the most dangerous mistakes clients make is assuming their annuity is fully liquid. Fixed and fixed indexed annuities typically come with a surrender period, often lasting seven to ten years. During this time, withdrawing more than a small percentage of your principal can trigger substantial surrender charges.
These charges are designed to compensate the insurance carrier for the cost of guarantees. If you need access to capital for a business opportunity or a medical emergency, these penalties can erode a significant portion of your wealth. We help clients evaluate whether their current annuity still fits their liquidity needs. If your financial situation has changed, a policy that was once appropriate may now be a trap.
Understanding the specific surrender schedule in your contract is the first step in protecting your capital. You can review your annuity options to see if a different structure better suits your current cash flow requirements.
Misunderstanding Index Credits and Caps
Fixed indexed annuities (FIAs) are often marketed as offering "market-like" growth without the risk. This is a partial truth that leads to disappointment. While FIAs protect your principal from direct market losses, the growth you receive is limited by participation rates, caps, and spreads.
A cap is the maximum interest rate the insurance company will credit to your account, regardless of how well the underlying index performs. If the S&P 500 rises by 20% in a given year, but your policy has a 10% cap, you will only receive 10% interest. Many clients review their policies years later, expecting higher returns, only to find their growth was artificially capped.
Additionally, some policies use a spread or margin fee, which is deducted from the index gain before it is credited to you. These mechanics are complex and rarely intuitive. We provide clarity on how fixed indexed annuities grow your money so you can set realistic expectations for your retirement income.
Overlooking Fee Erosion in Older Policies
Insurance products are not static. The fees associated with your policy, such as mortality and expense risk charges, can silently erode your value over time. In older policies, these fees may have been higher than current market standards, or the cost of guarantees may no longer be necessary for your risk profile.
Furthermore, inflation reduces the purchasing power of fixed payments. A guaranteed income stream that seemed substantial twenty years ago may now fall short of covering basic living expenses. Reviewing the real-world value of your benefits is crucial. We help clients assess whether their current income strategy provides adequate retirement income in today's economic environment.
Neglecting Beneficiary Designations and Estate Planning
Life insurance and annuities are powerful estate planning tools, but only if the paperwork is current. A common mistake is failing to update beneficiary designations after major life events such as marriage, divorce, or the birth of a child. If your designations are outdated, your assets may pass according to state law rather than your wishes.
This oversight can lead to unintended tax consequences and probate delays. For high-net-worth individuals, proper beneficiary structuring can minimize estate taxes and ensure a smoother transfer of wealth. We coordinate with specialized professionals to ensure your estate planning aligns with your insurance strategies.
Confusing Protection with Growth Potential
Another frequent error is using life insurance primarily for growth when its core strength is protection. Whole life insurance offers cash value accumulation, but it is not a high-growth investment vehicle compared to other assets. It is designed to provide a death benefit and a stable, predictable cash value component.
Conversely, some clients use annuities for aggressive growth, ignoring the tax implications of withdrawals. Understanding the distinct role of each product is essential. Life insurance protects your family's financial future, while annuities secure your own income. We help you evaluate life insurance strategies that balance cost, coverage, and cash value features effectively.
Failing to Coordinate with Broader Financial Strategy
Insurance policies do not exist in a vacuum. They must work in harmony with your tax situation, investment portfolio, and retirement goals. A common mistake is reviewing a policy in isolation, without considering how it interacts with Social Security, Medicare, or other retirement accounts.
For example, improper annuity distributions can increase your taxable income, potentially triggering higher Medicare premiums. Similarly, holding too much cash value in life insurance can complicate your estate tax liability. We take a holistic approach to tax-aware retirement strategies, ensuring every piece of your plan works together.
Comparison of Policy Review Focus Areas
| Policy Type | Primary Risk | Key Review Metric | Strategic Action |
|---|---|---|---|
| Fixed Indexed Annuity | Liquidity constraints | Surrender charge schedule | Evaluate cash flow needs |
| Whole Life Insurance | Cost of insurance | Dividend history | Assess cash value efficiency |
| Term Life Insurance | Expiration of coverage | Renewal premiums | Convert or replace if needed |
| Variable Annuity | Market risk | Underlying fund fees | Review investment options |
Key Takeaways
- Surrender charges can significantly reduce the value of early withdrawals from annuities.
- Index caps and participation rates limit the growth potential of fixed indexed annuities.
- Fee erosion in older policies can diminish long-term returns over time.
- Outdated beneficiary designations can lead to unintended estate tax consequences.
- Life insurance and annuities serve different primary purposes: protection vs. income.
- Insurance strategies must be coordinated with tax and estate planning goals.
- Regular reviews ensure your policies align with your current financial reality.
Frequently Asked Questions
How often should I review my annuity or life insurance policy?
We recommend reviewing your policies every three to five years, or after any major life event such as marriage, divorce, or retirement. Regular reviews ensure your coverage remains aligned with your goals.
What is a surrender charge in an annuity?
A surrender charge is a fee imposed by the insurance company if you withdraw more than the allowed free withdrawal amount during the surrender period. These charges typically decrease over time.
Can I change the beneficiary on my life insurance policy?
Yes, you can change the beneficiary on your life insurance policy by contacting your insurance carrier. It is important to ensure the change is properly documented and filed.
What is the difference between a fixed and fixed indexed annuity?
A fixed annuity offers a guaranteed interest rate, while a fixed indexed annuity's growth is linked to a market index but protected from market losses. Both offer principal protection, but the growth mechanisms differ.
How does life insurance affect estate taxes?
Life insurance proceeds are generally income-tax-free to beneficiaries. However, if the policy is owned by the insured, the death benefit may be included in their taxable estate. Proper ownership structuring can mitigate this.
What is privatized banking in relation to life insurance?
Privatized banking uses a whole life insurance policy as collateral to finance investments. This strategy allows you to access capital while your cash value continues to grow, maintaining liquidity and protection.
Take Control of Your Financial Future
Don't let outdated policies compromise your retirement security. At Generational Wealth Concepts, we provide comprehensive reviews to ensure your annuities and life insurance strategies support your income, protection, and legacy goals. Schedule a free strategy session today to discuss your specific needs and discover how we can help you build confidence in your financial future.
Schedule Your Financial Strategy Conversation